SEPTEMBER 2026
After the Rush
Late summer at Lake Tahoe has a particular quality to it — the crowds thin just enough, the light turns amber earlier, and the mountains start their slow reminder that fall is coming. The lake is as clear and warm as it gets, the trails are open, and anyone lucky enough to be in Incline Village right now is getting the best of what this place offers.
August produced 32 closings — one home at $8.5M that closed in 53 days at full asking price, three more above $5M, and a market working through a significant structural shift that requires more than a quick read of the summary numbers to understand.
The most important thing to know about 2026's data: the overall price metrics are being heavily influenced by a change in market composition, not by price appreciation or decline. SF prices are actually higher than last year by both median and dollar volume. The overall median looks lower because the condo market came back to life in a way not seen in this dataset. Getting that distinction right is the prerequisite for reading any number in this report correctly.
TOP MARKET STORIES
The Condo Surge That Changed Every Headline Number
Through August 2026, Incline Village has recorded 105 condo closings. In the same eight months of 2025, there were 27. That is not a rounding error — it is the single most consequential development in this market all year, and it is the key to reading almost every other metric correctly.
The activity is broad. Fifty of those 105 closings were priced below $1 million, across 47 different complexes. That sub-tier had only eight transactions in the same period of 2025, and fewer than that in 2022, 2023, and 2024. The market absorbed entry-level condo inventory at a pace not seen here since 2020.
105 condo closings through August. 47 different complexes. 50 closes below $1 million. The same tier had eight transactions in all of 2025.
What this means for every other number: when 78 additional condo transactions — many of them priced between $550,000 and $875,000 — are added to an already-active SF market, the combined median price falls. Not because values declined, but because the mix of what sold changed dramatically. The overall median of $1,550,000 reflects that mix shift; it is not a price trend.
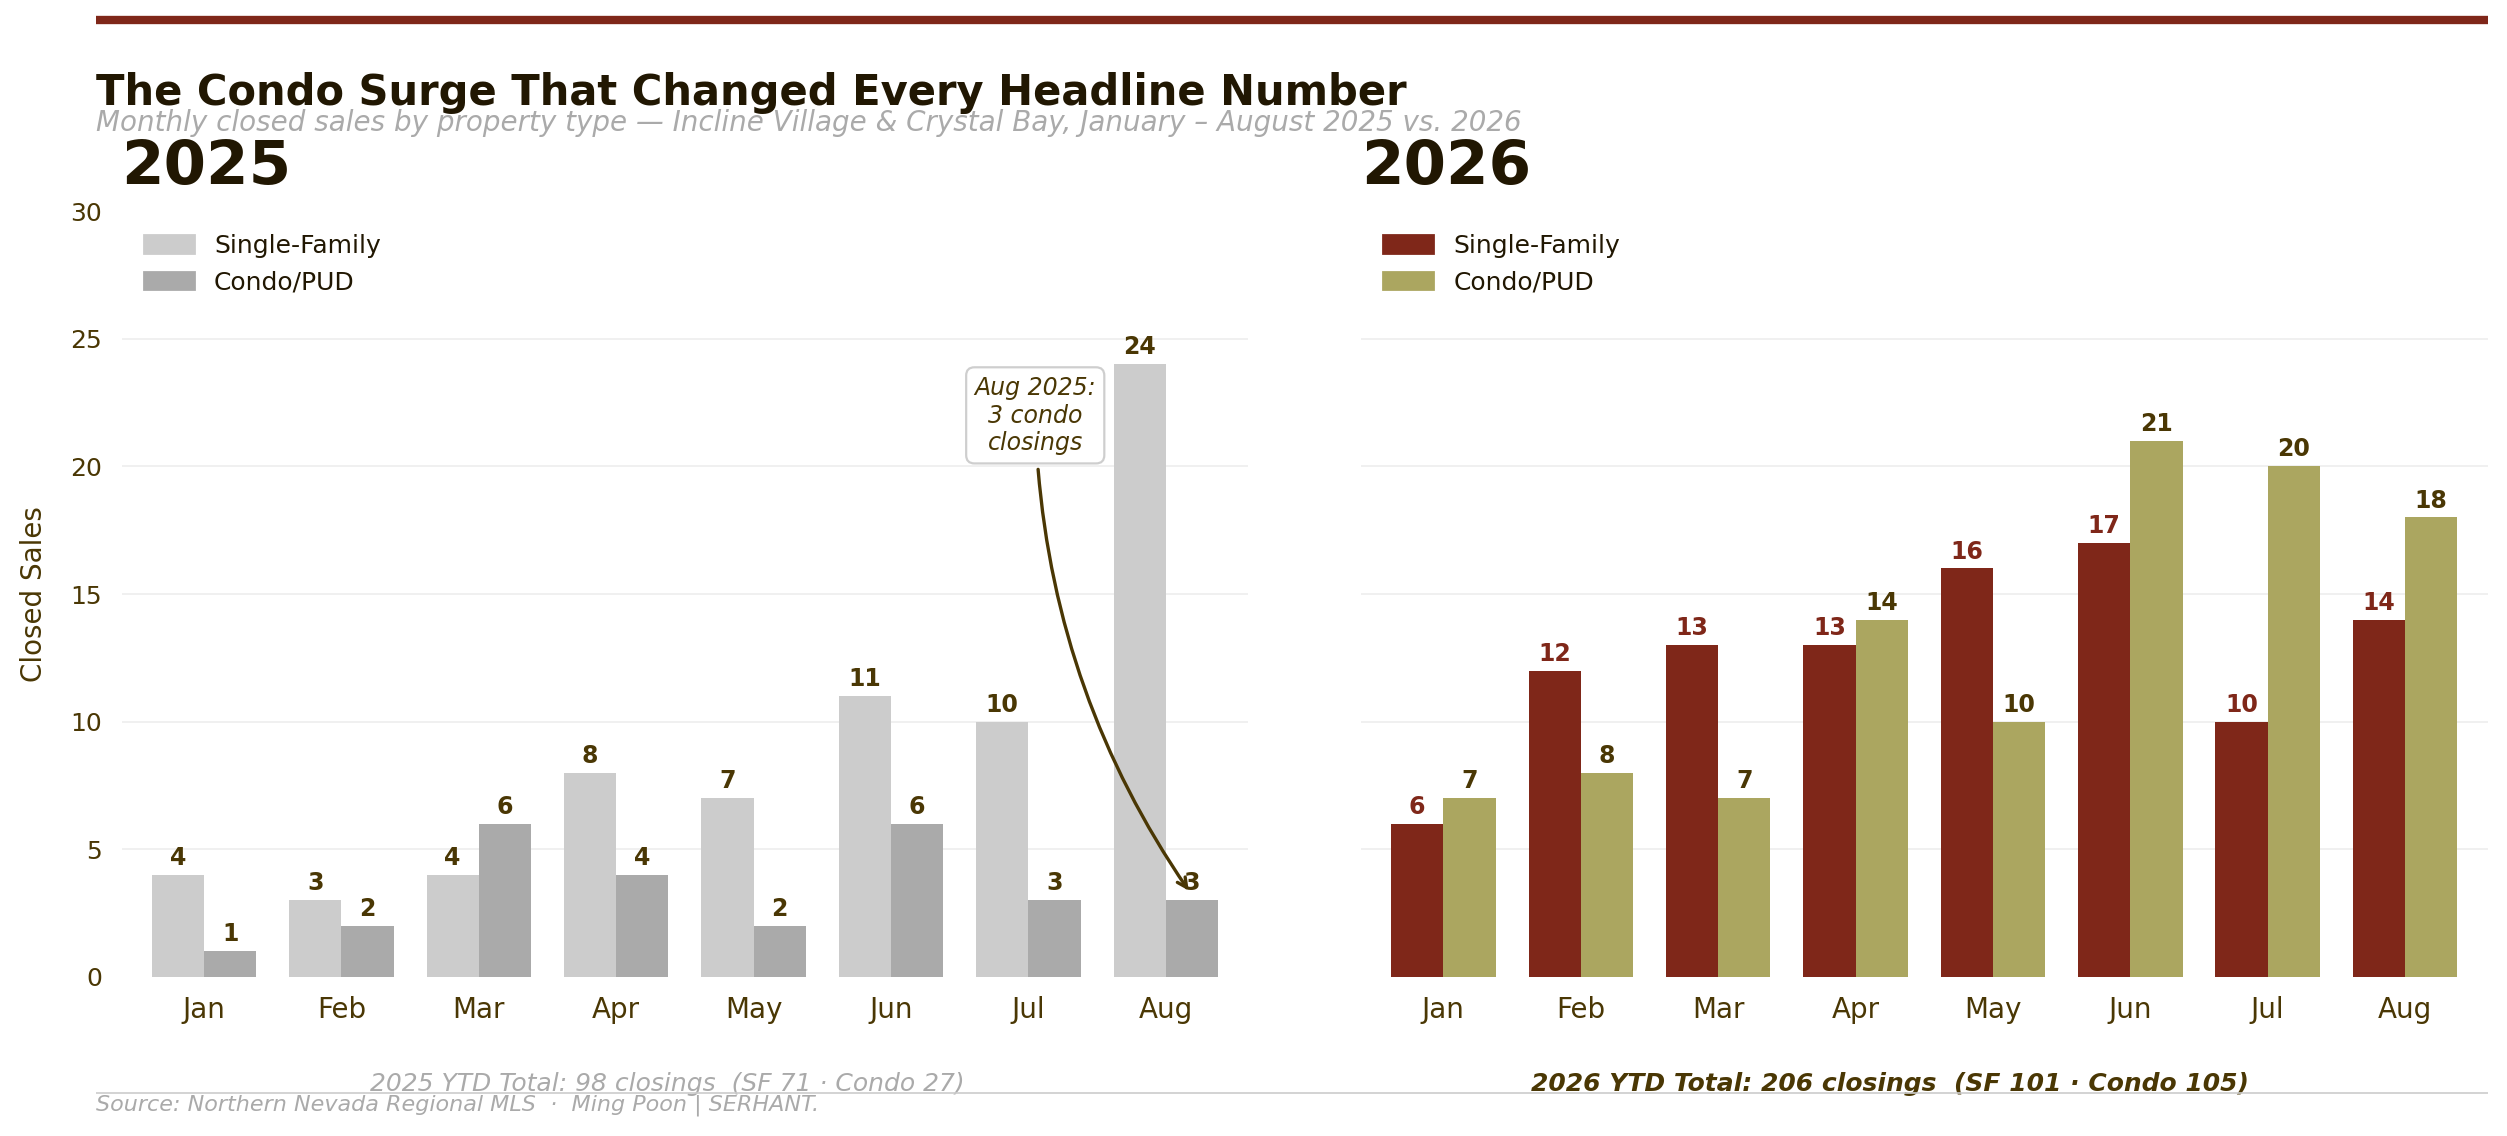
Monthly closed sales by property type — Incline Village & Crystal Bay, January–August 2025 vs. 2026. The condo surge across 47 complexes is the year's defining structural development.
The SF market, read on its own, tells a different story. The SF median for the first eight months closed at $2,510,000 — up 7.5% from $2,335,000 in the comparable 2025 period. But even that warrants care. Price-per-square-foot — the more reliable like-for-like measure — is down modestly: roughly flat in the $2M–$5M range and 4–6% below last year in the sub-$2M tier. The SF median has risen partly because the transaction mix shifted toward higher-value homes, not purely because the same home is worth more per square foot. The correct read: more activity at higher price points, with PPSF flat to slightly lower across most tiers.
The condo surge represents demand meeting price levels that had not been broadly available in this market since 2020. That is a meaningful development. It also means any reader comparing the 2026 overall median to 2025 without this context will draw the wrong conclusion.
The condo surge has a direct effect on every pricing headline. Here is what the segment decomposition shows.
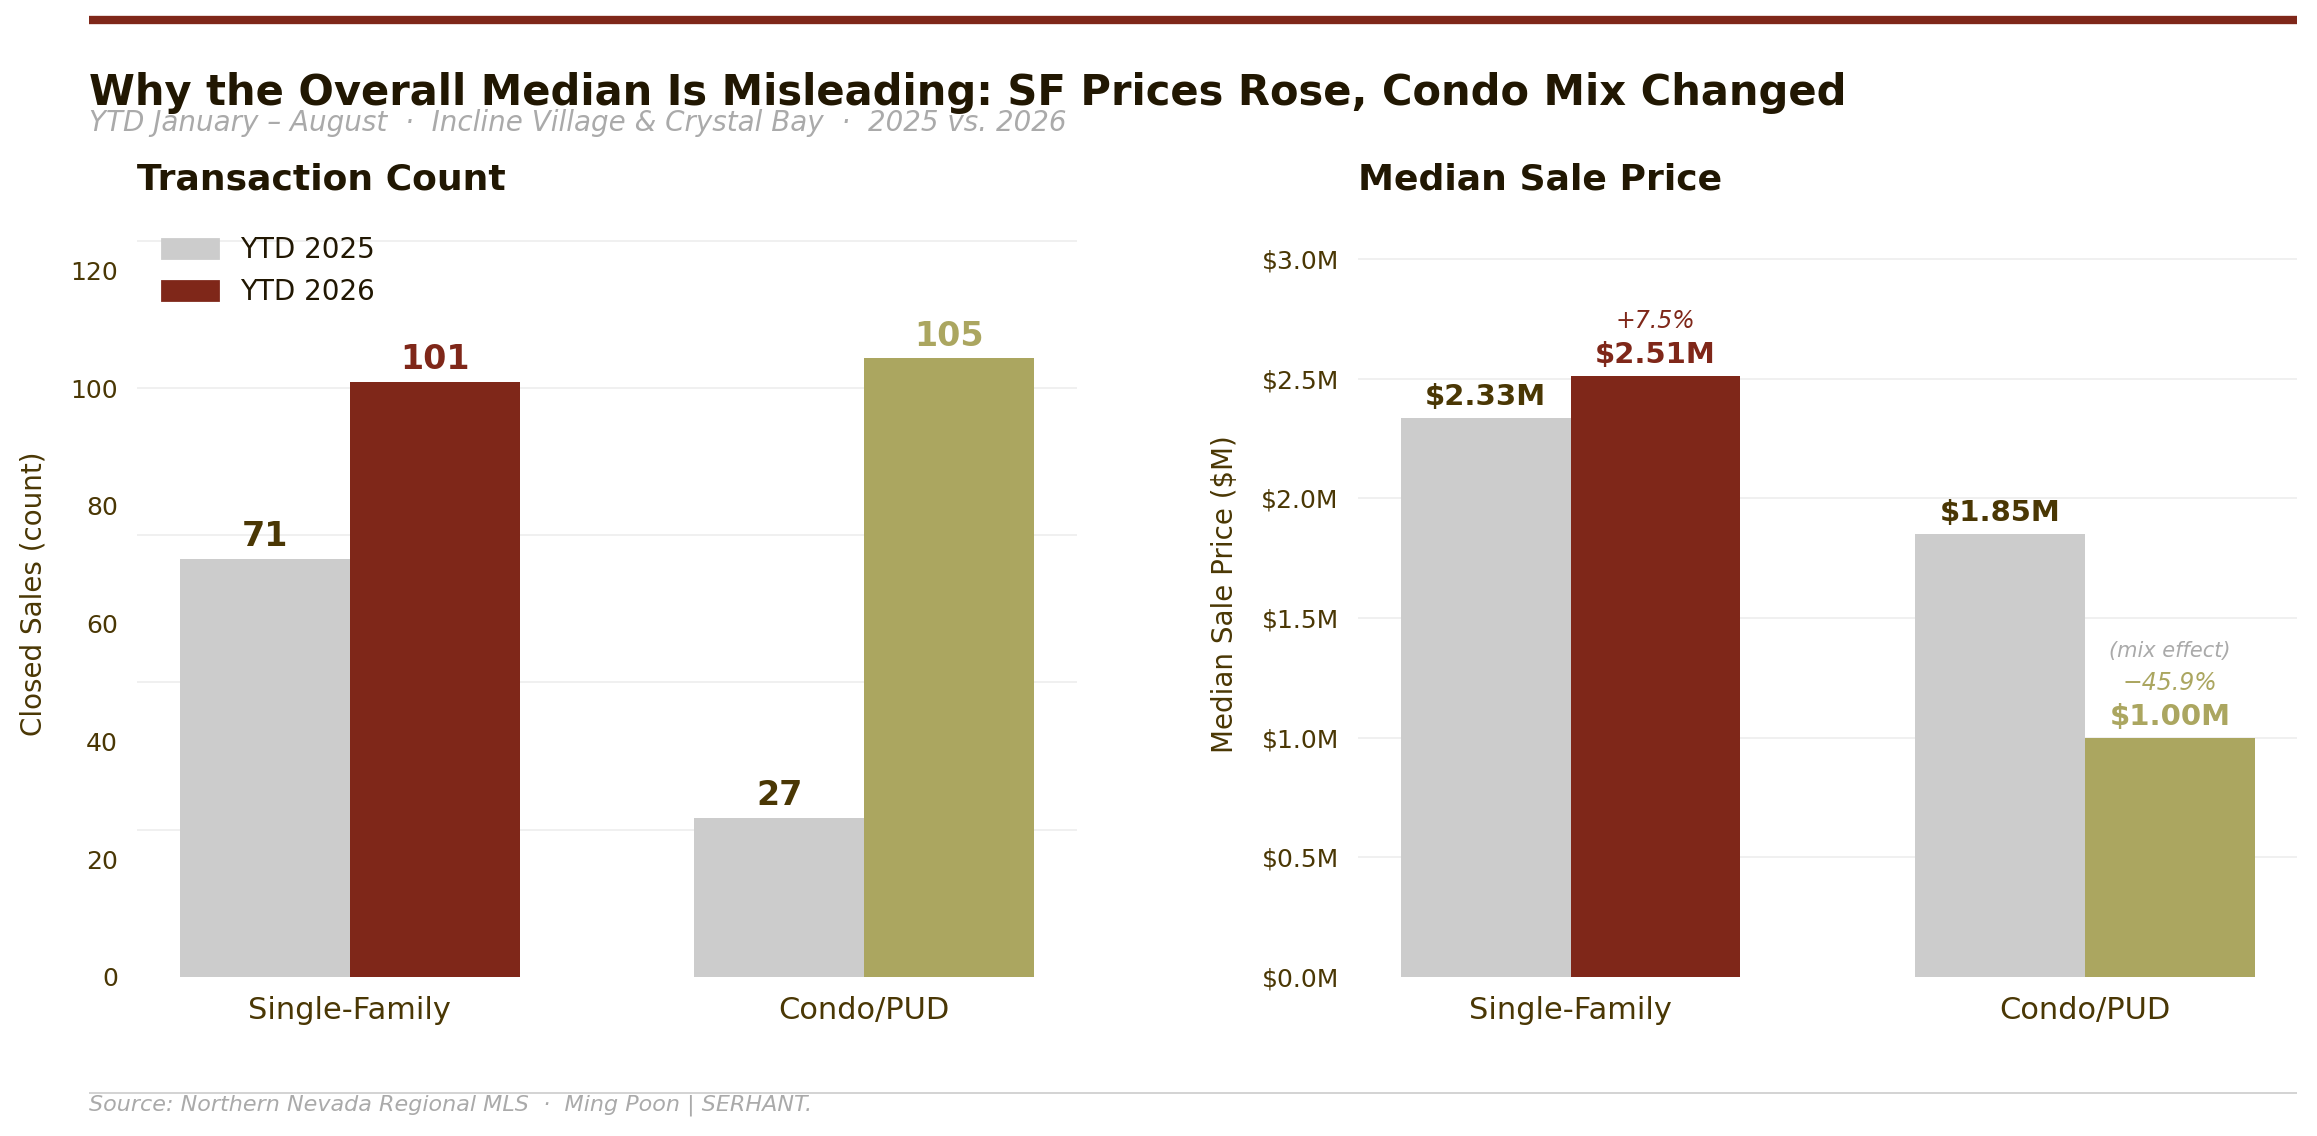
YTD January–August, Incline Village & Crystal Bay. SF median rose 7.5%; the condo median shift reflects a structural change in what is selling, not a price decline.
The SF Market Rebalanced — That Is Not the Same as Weakening
In May 2026, the single-family market was running at 3.7 months of supply — a seller's market by any conventional measure. By August, that figure had moved to 6.1 months. Six months is the conventional boundary between a seller's market and a balanced one.
This is what a spring surge looks like when it normalizes. Within 2026, the absorption arc is clear: active SF inventory grew from 53 listings in January to 87 in July before a marginal pull-back to 86 in August.
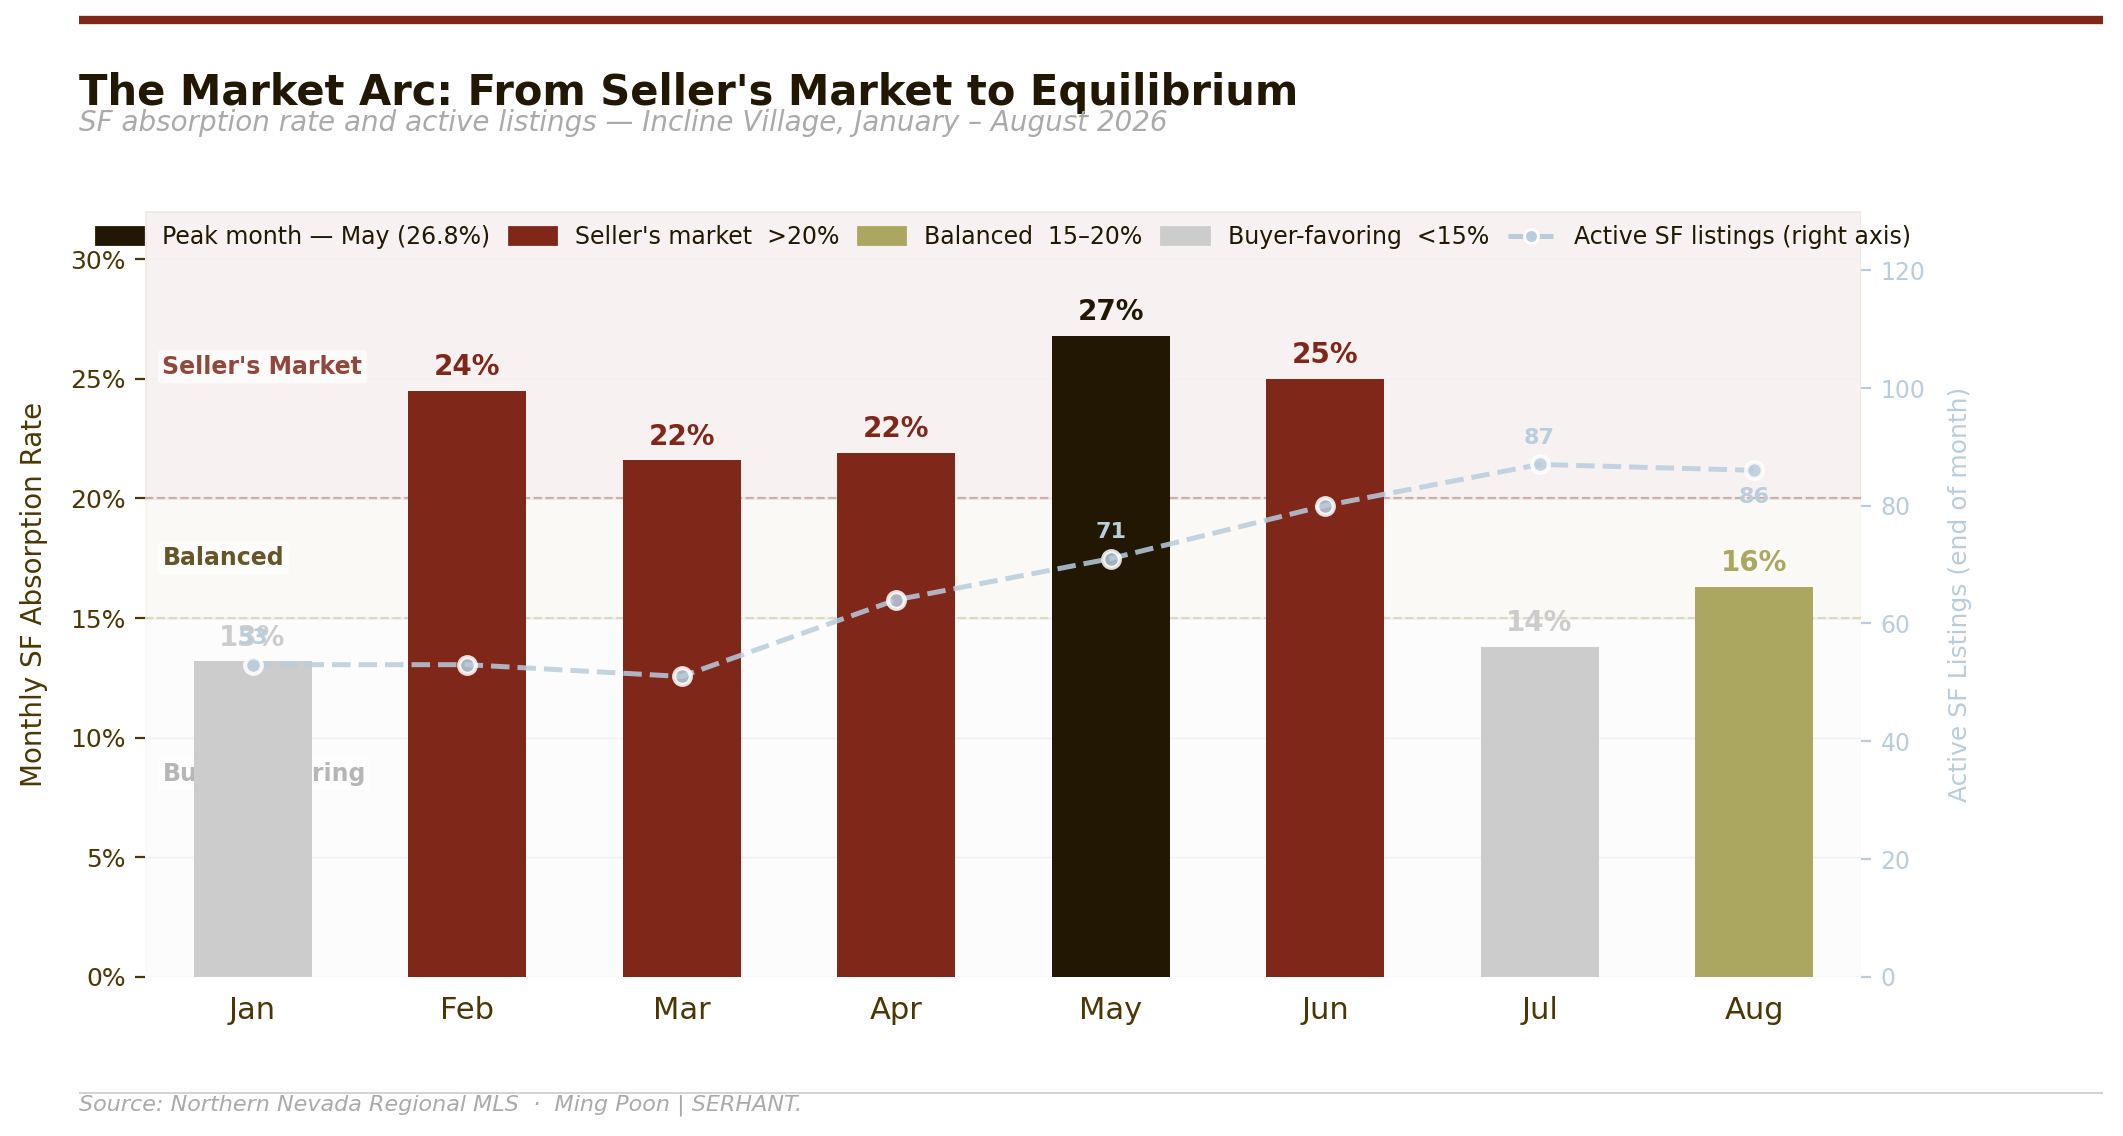
SF monthly absorption rate (bars) and active SF listings (line) — Incline Village, January–August 2026. May's 26.8% absorption (3.7 months of supply) defined the spring seller's market; August's 16.3% (6.1 months) marks equilibrium.
The SF absorption rate — closed sales as a percentage of available listings — ran 13% in January, 27% in May, 14% in July, 16% in August. Spring was a seller's market. Late summer is equilibrium.
For sellers, equilibrium means correctly priced property still moves — just not as quickly or easily as it did in May. The active listing data confirms this precisely: 27% of active SF listings (20 of 74) have already been reduced more than 5% from their original asking price and remain unsold.
For buyers, equilibrium means more room to evaluate, more time to negotiate, and less urgency around correctly priced properties than earlier in the year. The 42 properties under contract heading into September — 15 SF contingent, 8 SF pending — suggest the market remains active at the right price points.
The Pricing Gap Is Measurable — and Wide
Two August transactions tell the story more clearly than any statistic.
563 Knotty Pine Drive: $8,500,000. 53 days on market. 100.1% of asking price. The seller priced it accurately from day one. The buyer didn't negotiate.
250 Pine Cone Road: $6,500,000. 179 days on market. 93.5% of the final list price — which was itself 18.2% below the original ask. The property closed. It required six additional months and a $1.45M price correction from where it started.
Both closed in August. Both are in the upper luxury tier. Both found buyers. The difference is entirely in how they were introduced to the market.
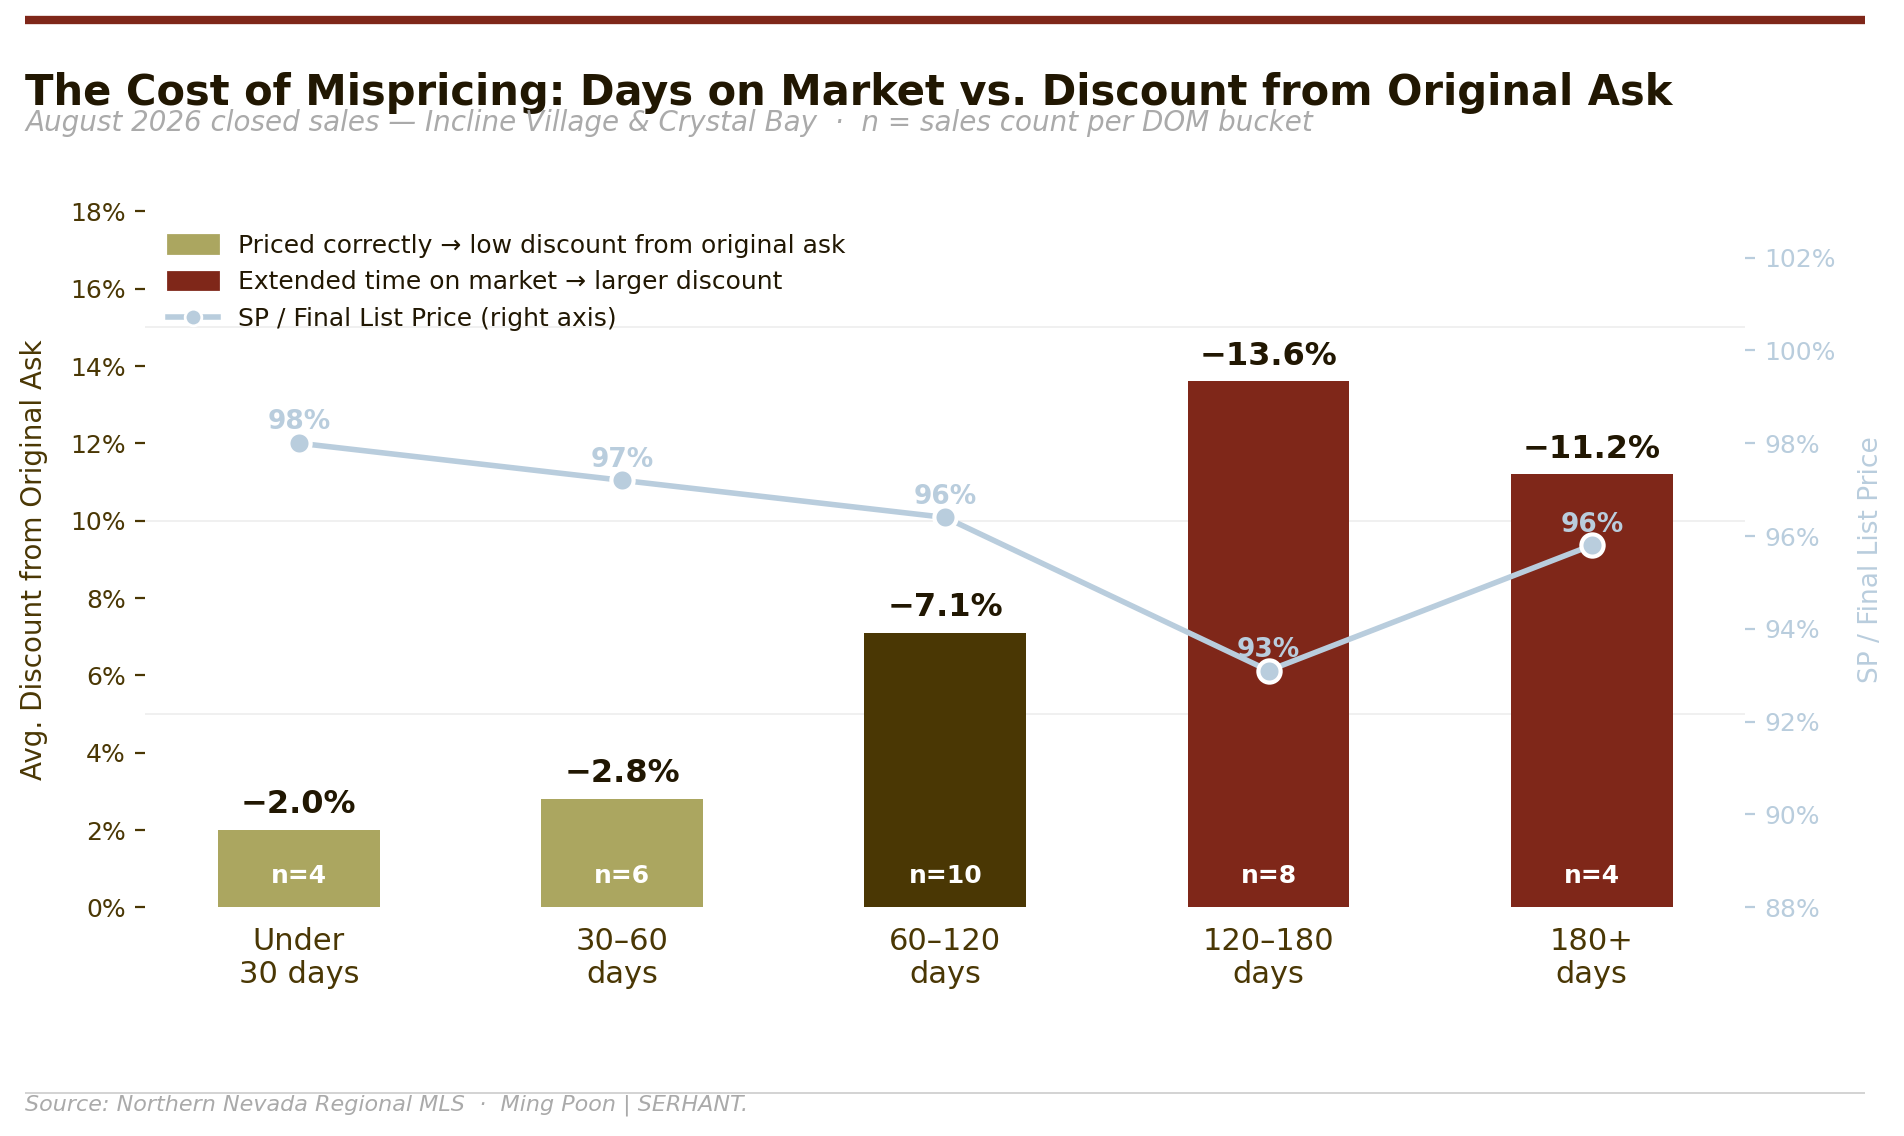
August 2026 closed sales — Incline Village & Crystal Bay. Average discount from original asking price by days-on-market bucket. n = sales count shown inside each bar.
The pattern appears across the price spectrum. August closings with DOM under 60 days averaged 97.5% of their final list price. The four closings with DOM above 180 days averaged 95.8% of final list — but those final list prices already reflected significant reductions from where those sellers started. The true negotiation from original asking price, across all August closings, averaged 7.8%. That figure — not the headline 95.9% SP/LP — is the more accurate measure of where buyers and sellers are actually meeting.
Lake Tahoe, Incline Village, Nevada
LUXURY & LAKEFRONT
Selective, Not Surging
August produced four closings above $5 million, accounting for 42% of the month's total volume. Before reading the year-over-year comparison — seven luxury closings in August 2025 versus four this year — the context matters. Last August included three sales above $10 million totaling $60 million: 1013 Lakeshore at $37.5M, 541 Skylake at $12.5M, and 422 Gonowabie at $10M. Without those three, August 2025's remaining 24 closings produced $75.4 million in volume. August 2026's 31 non-$10M+ closings produced $73.8 million. On a like-for-like basis, the months are comparable.
Of the four August luxury transactions, one is straightforward and three are not. The $8.5M Knotty Pine Drive close — 53 days, at full ask — required no negotiation. The other three each involved meaningful time and price negotiation: 571 Dale Drive at 96.5% of ask after 124 days, 120 State Route 28 Unit 47 (Crystal Bay lakefront) at 96.9% of ask after 111 days, and 250 Pine Cone Road at 93.5% of a final list that was already 18% below original. These are completed transactions — the market cleared them — but they are not evidence of a competitive luxury market.
Year-to-date, the $5M+ count stands at 26 transactions — the highest for this market through August in any year in the dataset, ahead of the 24 recorded through the same period in 2021. Removing the $46 million February record leaves 25 sales at $243.8 million, also a multi-year high through August. The luxury market has been genuinely more active in 2026 than in any comparable period since 2021. What it has not been is a market where buyers are paying aspirational prices: across the 26 $5M+ YTD closings, discounts from original asking price are the rule, not the exception.
Seven Transactions. $110.7 Million. Disciplined Buyers.
Seven confirmed direct-frontage lakefront closings year-to-date, against two in the same period of 2025. That is a meaningful increase by count. How those seven transactions happened matters as much as the fact that they did.
The year opened with the February close of 919 Lakeshore Boulevard at $46 million — 0 days on market, suggesting a pre-arranged transaction before any public listing. That sale set the year's ceiling and its character: a specific property meeting a specific buyer under specific circumstances. Everything since has operated at a different pace.
The remaining six YTD lakefront closings averaged 148 days on market and closed at an average of 8.2% below their original asking price. 460 Gonowabie Road — a direct-frontage SF lakefront home in Crystal Bay — took 436 days and closed 13.6% below a $29.5 million original ask. 260 Northlake Circle closed at 86.8% of original list after 80 days. These are not bidding-war outcomes. They are patient negotiations between serious buyers and sellers who found agreement — eventually.
Of the seven YTD lakefront closings, four are condo or PUD units and three are standalone SF homes. Crystal Bay accounts for four of the seven, including the August close at 120 State Route 28 Unit 47 — a Stillwater Cove lakefront condo that traded at $10.65 million after 111 days at 96.9% of ask. Note: 501 Lakeshore Boulevard Unit 33 (August close, $3.525 million) is within the Lakeshore Terrace lakefront community but is a back-row unit without direct lake frontage; it is not counted in the seven.
Seven lakefront transactions, $110.7 million, and not one of them closed at or above its original asking price. This is an active lakefront market. It is not a competitive one.
scroll →
Address | City | Date | Price | DOM | Disc. from OLP | Type |
|---|---|---|---|---|---|---|
919 Lakeshore Blvd | IV | Feb 13 | $46.0M | 0d | −3.2% | SF |
460 Gonowabie RD | CB | Mar 20 | $25.5M | 436d | −13.6% | SF |
260 Northlake CIR | CB | Jun 8 | $13.8M | 80d | −13.2% | SF |
120 SR 28 Unit#47 | CB | Aug 20 | $10.65M | 111d | −3.1% | Condo/PUD |
120 SR 28 Unit#3 | CB | Feb 12 | $5.9M | 115d | −5.6% | Condo/PUD |
525 Lakeshore Unit#74 | IV | May 5 | $4.675M | 91d | −3.6% | Condo/PUD |
549 Lakeshore Unit#16 | IV | Apr 22 | $4.2M | 55d | −15.2% | Condo/PUD |
IV = Incline Village · CB = Crystal Bay · OLP = Original List Price
501 Lakeshore BLVD Unit#33 excluded — back-row unit, not direct lake frontage
August in Historical Context
August 2026 closed 32 transactions — above the historical August average. The volume comparison to 2025 requires context before drawing any conclusions.
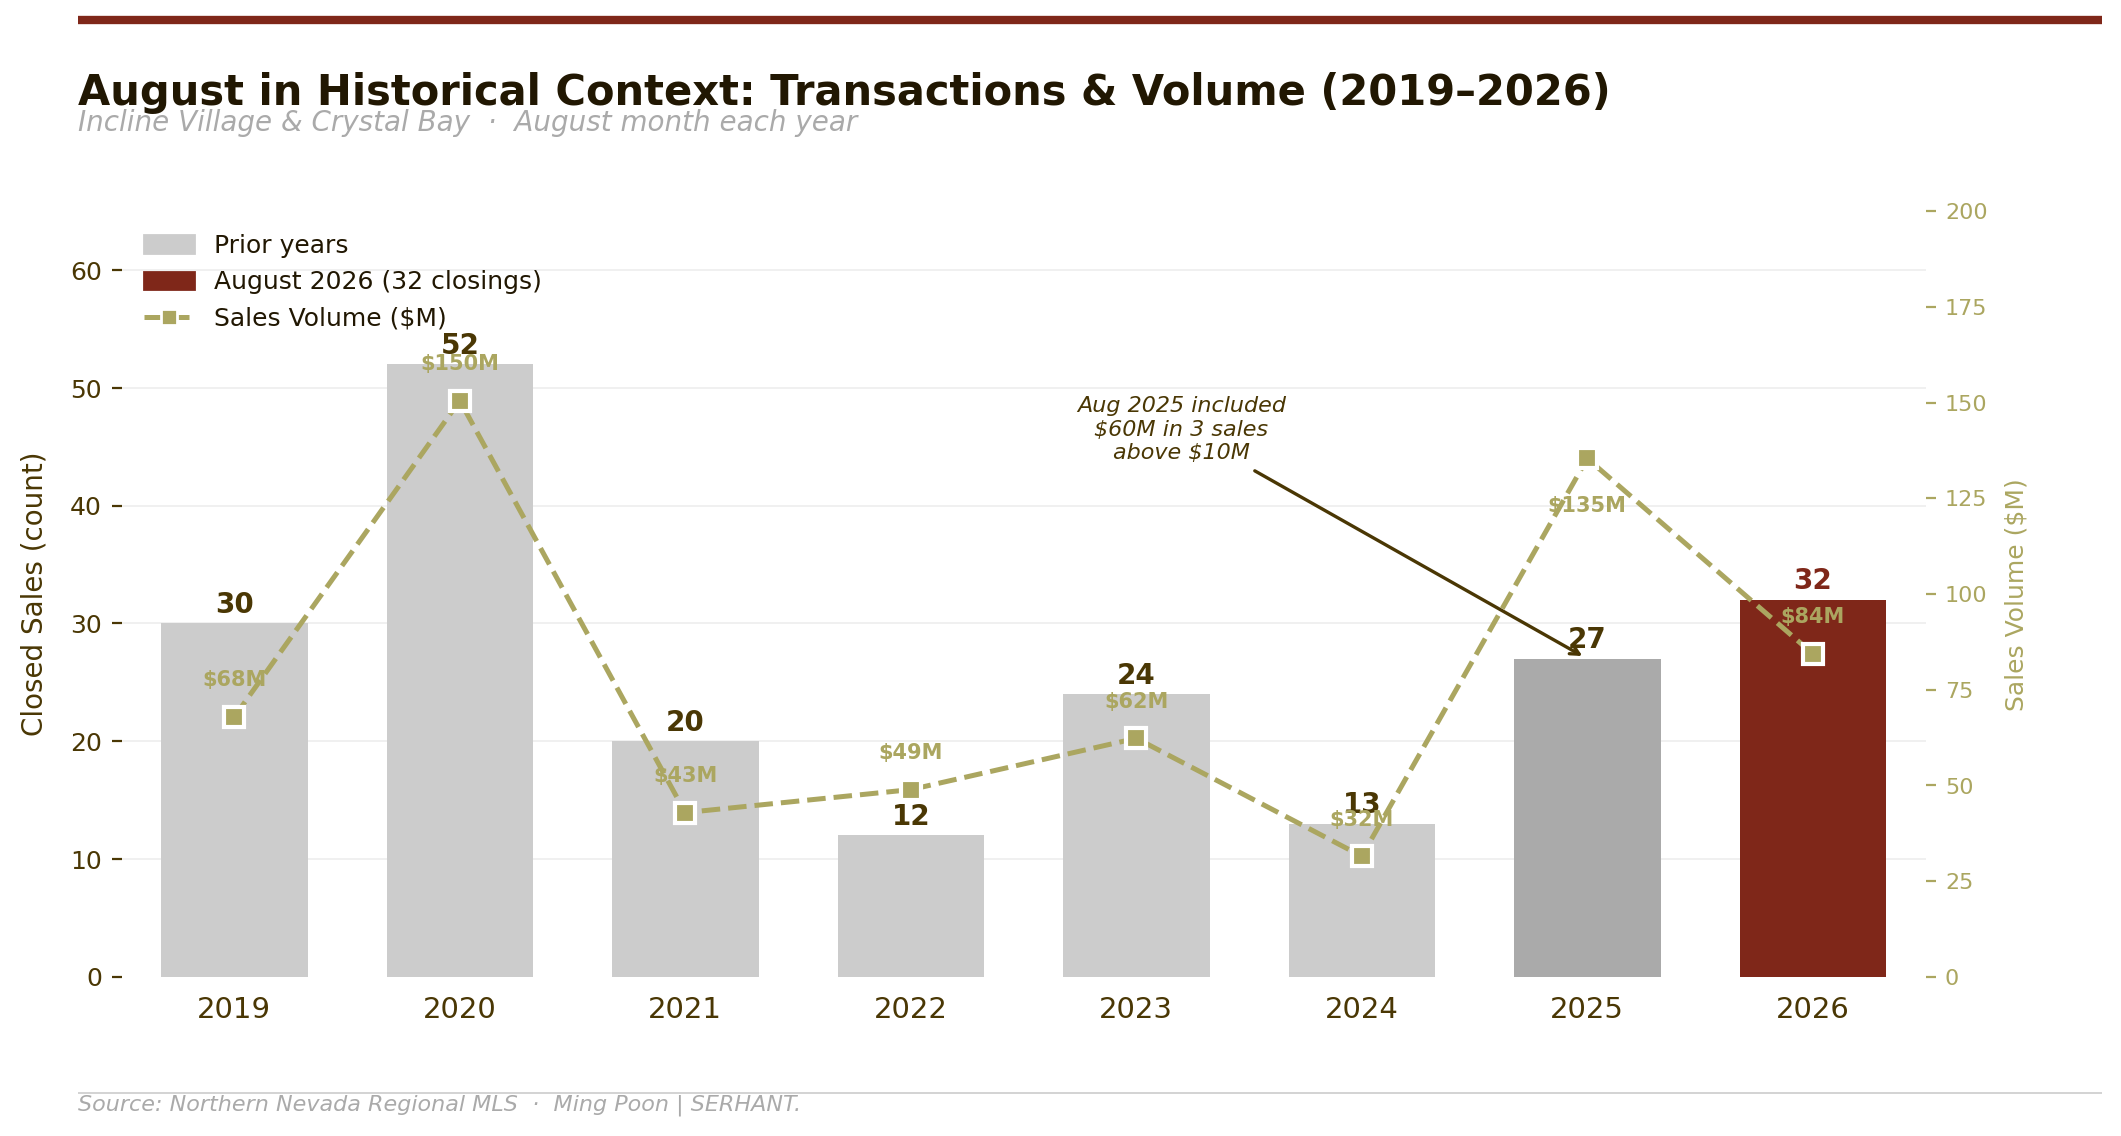
August closed sales and volume — Incline Village & Crystal Bay, 2019–2026. August 2025's $135.4M volume included three sales above $10M totaling $60M; excluding those, August 2025 and 2026 were comparable on a like-for-like basis.
Two Markets. One Zip Code.
Incline Village
Incline Village is carrying the market. Through August, 199 of the combined 206 closings occurred here. The condo surge is exclusively an IV story — all 105 YTD condo closings are in Incline Village, spread across 47 complexes. The SF market has run 97 closings at a median of $2,500,000, outpacing 2025 by 37% in transaction count and 34% in SF volume.
August specifically: 31 of 32 closings were Incline Village. The 14 IV SF closings carried a median of $2,987,500 — meaningfully above August 2025's $2,775,000 IV SF median, though that reflects transaction mix as much as underlying price movement. The active inventory picture is the one to watch: 20 of 74 active SF listings (27%) have already taken price reductions greater than 5% from original list and remain unsold. The market is absorbing correctly priced inventory. It is not absorbing overpriced inventory.
Crystal Bay
Crystal Bay is a different market in almost every meaningful way. One closing in August — 120 State Route 28 Unit 47 at $10.65 million — is a significant event for a market that produces six to twelve transactions in an entire year. No conclusions about Crystal Bay's monthly trend are possible from a single transaction, and none should be drawn.
What the YTD data does show: seven CB closings, nearly all concentrated in lakefront and upper-luxury product. Two non-lakefront CB transactions this year — 240 State Route 28 ($3.2 million, 232 DOM) and 355 Tuscarora ($685,000, 634 DOM) — illustrate that the non-lakefront CB residential segment is considerably thinner and slower. CB's dollar volume is a lakefront story. The broader CB residential market had fewer transactions this year than last (7 vs. 8), concentrated at higher price points.
Eleven active listings remain in Crystal Bay, from $950,000 to $45 million. The withdrawn listing at 475 Tuscarora — $10.7 million, withdrawn after 211 days and a 10% price reduction — confirms that aspirational pricing is not absorbed in CB any more readily than anywhere else in this market.
MING'S PERSPECTIVE
What the Data Shows, and What I'm Seeing
The data tells me August was a normal month for this market — perhaps a good one, when stripped of comparison to an outlier-driven August 2025. Thirty-two closings is above the historical August average. The SF market is in equilibrium. The condo market is absorbing inventory that needed to clear. The 42 properties under contract suggest September will be active.
What I am seeing on the ground adds texture. Buyers who have been watching this market for months are aware that the spring urgency has faded. More requests for second showings. More thorough inspection periods. More willingness to walk away when terms aren't right. That is what a balanced market feels like from the inside. It means buyers have room to be deliberate, and sellers need to understand that pricing strategy from the May market doesn't translate to August.
On the seller side, I am having more pricing conversations than at any point this year. The gap between where a seller wants to start and where the market will meet them has widened since spring. The active listing data reflects it: 20 SF listings have been reduced more than 5% and remain unsold. The sellers who priced accurately from day one are closing. The ones who tested the market are recalibrating.
The condo surge is something I want to understand more fully before characterizing it broadly. The scale — 47 different complexes absorbing 105 closings through August — suggests entry-level and mid-range buyers have returned in real numbers, likely finding entry points in condos that are priced more realistically than they were during the 2021–2022 run-up. If that holds into fall, it has implications for the entry-level SF market above it. But it is one year of data, and one year is not a trend.
The market I am operating in right now rewards early, accurate pricing. It does not reward testing the ceiling or assuming the spring's conditions still apply. For buyers, this fall may offer more room than any period in the past two years.
LOOKING AHEAD
What I'll Be Watching in September
The 42 properties under contract are the most important leading indicator. Three SF properties above $5 million are contingent or pending — if they close, September's luxury numbers will look materially different from August's. The pending pipeline skews condo-heavy below $2M (eight of eleven pending are condos) and SF-heavy above $3M (seven of eleven SF deals above $3M). Expect September's composition to reflect that.
The SF absorption rate is what I'll watch most carefully. At 6.1 months of supply entering September, the market is balanced. If absorption holds in the 15–20% range, equilibrium continues. If active listings decline seasonally while sales stay consistent, the supply picture could tighten meaningfully — not because demand increased, but because fewer sellers choose to list into a fall market.
The condo market's pace is the second thing to watch. One hundred and five closings through August against a prior norm of 15–45 for the same period is extraordinary. September will begin to tell us whether the most accessible inventory has cleared or whether the pace continues.
Seven expired listings and eight withdrawn in the August file — several with DOM above 300 days — represent sellers who have not yet reconciled with market pricing. How they re-enter (or don't) will shape available SF inventory through fall. A wave of relists at adjusted prices could push supply higher; permanent withdrawals would have the opposite effect.
DATA REFERENCE
Key Statistics
August 2026 — Month-over-Month
scroll →
Metric | July 2026 | August 2026 | MoM Change |
|---|---|---|---|
Total Closings | 30 | 32 | +6.7% |
Total Volume | $61.0M | $84.4M | +38.4% |
Overall Median | $1,235,000 | $1,550,000 | +25.5% (mix effect) |
SF Closings | 10 | 14 | +40.0% |
SF Median | $2,250,000 | $2,987,500 | +32.8% (mix effect) |
Condo Closings | 20 | 18 | −10.0% |
Condo Median | $1,035,000 | $967,500 | −6.5% |
Median DOM | 66d | 95d | +45.0% |
Avg SP / Final List | 97.6% | 95.9% | −1.7 pts |
Avg SP / Original Ask | est. 94% | 92.2% | — |
At or Over Ask | 9 (30%) | 4 (12.5%) | −17.5 pts |
$5M+ Sales | 3 | 4 | +1 |
$10M+ Sales | 0 | 1 | +1 |
Lakefront Closes | 0 | 1 | — |
“Mix effect” indicates the change reflects a shift in property-type composition rather than price appreciation or decline. See analysis.
August 2026 — Year-over-Year
August 2025 volume included three sales above $10M totaling $60M (1013 Lakeshore at $37.5M, 541 Skylake at $12.5M, 422 Gonowabie at $10M). Excluding those three, August 2025 produced $75.4M across 24 transactions — comparable to August 2026 on a like-for-like basis.
scroll →
Metric | Aug 2025 | Aug 2026 | YoY Change |
|---|---|---|---|
Total Closings | 27 | 32 | +18.5% |
Total Volume | $135.4M | $84.4M | −37.6% * |
Overall Median | $2,700,000 | $1,550,000 | −42.6% (mix effect) |
SF Closings | 24 | 14 | −41.7% |
SF Median | $2,775,000 | $2,987,500 | +7.7% |
Condo Closings | 3 | 18 | +500.0% |
Condo Median | $2,700,000 | $967,500 | Not comparable |
Median DOM | 81d | 95d | +17.3% |
Avg SP / Final List | 95.9% | 95.9% | Flat |
SF Median PPSF | $1,129 | $931 | −17.5% (mix effect) |
$5M+ Sales | 7 | 4 | −42.9% |
$10M+ Sales | 3 | 1 | −66.7% |
Lakefront | 2 | 1 | −1 |
YTD 2026 (Jan–Aug) vs. YTD 2025
scroll →
Metric | YTD 2025 | YTD 2026 | Change |
|---|---|---|---|
Total Closings | 98 | 206 | +110.2% |
Total Volume | $327.6M | $601.3M | +83.6% |
Overall Median | $2,150,000 | $1,586,500 | −26.2% (mix effect) |
SF Closings | 71 | 101 | +42.3% |
SF Median | $2,335,000 | $2,510,000 | +7.5% (partial mix effect) |
Condo Closings | 27 | 105 | +288.9% |
Condo Median | $1,850,000 | $1,000,000 | Not comparable |
Median DOM | 80d | 72d | −10.0% |
Avg SP / Final List | 95.35% | 96.15% | +0.8 pts |
SF PPSF (median) | $947 | $930 | −1.8% |
$5M+ Sales | 14 | 26 | +85.7% |
$10M+ Sales | 5 | 11 | +120.0% |
Lakefront Sales | 2 | 7 | +250.0% |
IV Closings | 90 | 199 | +121.1% |
CB Closings | 8 | 7 | −12.5% |
SF Absorption Rate — 2026
Source: SF-only active inventory reference table maintained by Ming Poon (end-of-month counts). No prior-year active inventory data is available; no year-over-year inventory comparison is made.
scroll →
Month | SF Active | SF Closed | Absorption Rate | Months of Supply |
|---|---|---|---|---|
January | 53 | 7 | 13.2% | 7.6 months |
February | 53 | 13 | 24.5% | 4.1 months |
March | 51 | 11 | 21.6% | 4.6 months |
April | 64 | 14 | 21.9% | 4.6 months |
May | 71 | 19 | 26.8% | 3.7 months ← seller's market |
June | 80 | 20 | 25.0% | 4.0 months |
July | 87 | 12 | 13.8% | 7.2 months |
August | 86 | 14 | 16.3% | 6.1 months ← balanced |
August 2026: Notable Sales
scroll →
Address | Price | DOM | SP / Orig Ask | Notes |
|---|---|---|---|---|
563 Knotty Pine Drive | $8,500,000 | 53d | 100.1% | IV SF — at ask |
120 SR 28 Unit#47 | $10,650,000 | 111d | 96.9% | CB — Stillwater Cove lakefront condo |
571 Dale Drive | $9,600,000 | 124d | 96.5% | IV SF — panoramic lake views |
250 Pine Cone Road | $6,500,000 | 179d | 81.8% | IV SF — 18.2% below original ask |
429 Valerie Court | $4,900,000 | 50d | 94.2% | IV SF — Upper Tyner |
610 Doeskin Court | $1,925,000 | 0d | 100.0% | IV SF — 0 DOM, full ask |
501 Lakeshore Unit#33 | $3,525,000 | 44d | 99.3% | Lakeshore Terrace — back row, not direct lakefront |
585 Village BLVD | $1,800,000 | 532d | 81.8% | IV SF — listed 2024, sold 2026 |
Thank you for reading The Incline Brief. If anything here raised a question about a specific property, neighborhood, or how the market might affect your plans as a buyer, seller, or someone thinking ahead — I'd genuinely enjoy that conversation. This market has more texture than any monthly report can fully capture, and the most useful discussions are usually the specific ones.
Summer at Tahoe doesn't last forever. But it leaves a mark that makes the fall worth looking forward to.
Serhant Nevada LLC · License B.0146327 · 6671 S Las Vegas Blvd #210
Las Vegas, NV 89119 · (702) 232-7678
All transaction data sourced from the Northern Nevada Regional MLS (NNRMLS), reflecting closed sales within Incline Village and Crystal Bay by close date. August 2026 figures sourced from the August 2026 MLS export (authoritative); YTD figures assembled from the July 2026 YTD file plus August 2026 sold records; historical comparisons reference the 2002–2025 all-sold file. Single-family homes identified as residential properties without an MLS complex name; condominiums by complex affiliation. 501 Lakeshore BLVD Unit#33 excluded from lakefront count: back-row unit in a lakefront community, not direct lake frontage. DOM reflects listing-period days as reported in MLS. Sale-to-list ratios calculated against final list price at offer acceptance; original list price comparisons noted separately throughout. SF active inventory figures sourced from the SF-only reference table maintained by Ming Poon (end-of-month). No prior-year active inventory data is available; no year-over-year inventory directional comparison is made. This report does not attribute buyer or seller representation to any transaction unless independently confirmed. For informational purposes only; not investment, legal, or financial advice. All figures should be independently verified. © 2026 Ming Poon | SERHANT. All rights reserved.