
THE MARKET JUST HIT AN ALL-TIME HIGH. QUIETLY.
No frenzy. No headlines. No bidding wars dominating dinner conversations the way they did in 2021. Just a steady accumulation of qualified buyers making considered decisions — and a July that produced the highest median sold price ever recorded in this market.
$1,286,250.
That number surpasses every prior July in thirteen years of data — including the pandemic-era peaks that felt impossible at the time. And it arrived in a market that looks nothing like those years. No 9-day median. No waived inspections and blind overbids. No desperation on either side of the transaction. Just a market that has been building toward something, and in July, got there.
I've been watching this market since 2002. The cycles are familiar. This one is different — not because the numbers are high, but because of how they got there.
$1,286,250
July 2026 Median Sold Price
All-Time High — Tahoe Sierra MLS
WHAT JULY SHOWED US
One hundred and fourteen closings. The highest July transaction count since 2020, the year the pandemic sent the entire country toward the mountains and every available piece of property that wasn't in a city. But 2020 was chaos dressed up as a real estate market. 2026 is something else: deliberate, orderly, and building.
The median days on market in July was 13.5. For reference: July 2025 was 21 days. July 2024 was 15. That 36% improvement in velocity, happening simultaneously with a price record, tells you something important about the nature of demand right now. These are not buyers chasing a market out of fear. They are buyers who have done their homework, know what they want, and move when they find it. That kind of decisiveness doesn't produce bubbles. It produces floors.
Sale-to-list ratio held at 99.2%. The median discount from original list price was just 1.7% across all sales — and only 2.6% in the $2M+ segment, which spent much of the spring absorbing inventory at wider discounts. The market is tightening from both ends: sellers holding closer to ask, buyers not waiting for a better number.
Month over month, July extended what June started. Ninety-five closings in June became 114 in July. The median rose from $1,195,000 to $1,286,250. Days on market held flat at 13 to 13.5 days. The spring momentum didn't peak in June and roll over. It kept going. Peak summer validated what the spring data was signaling.
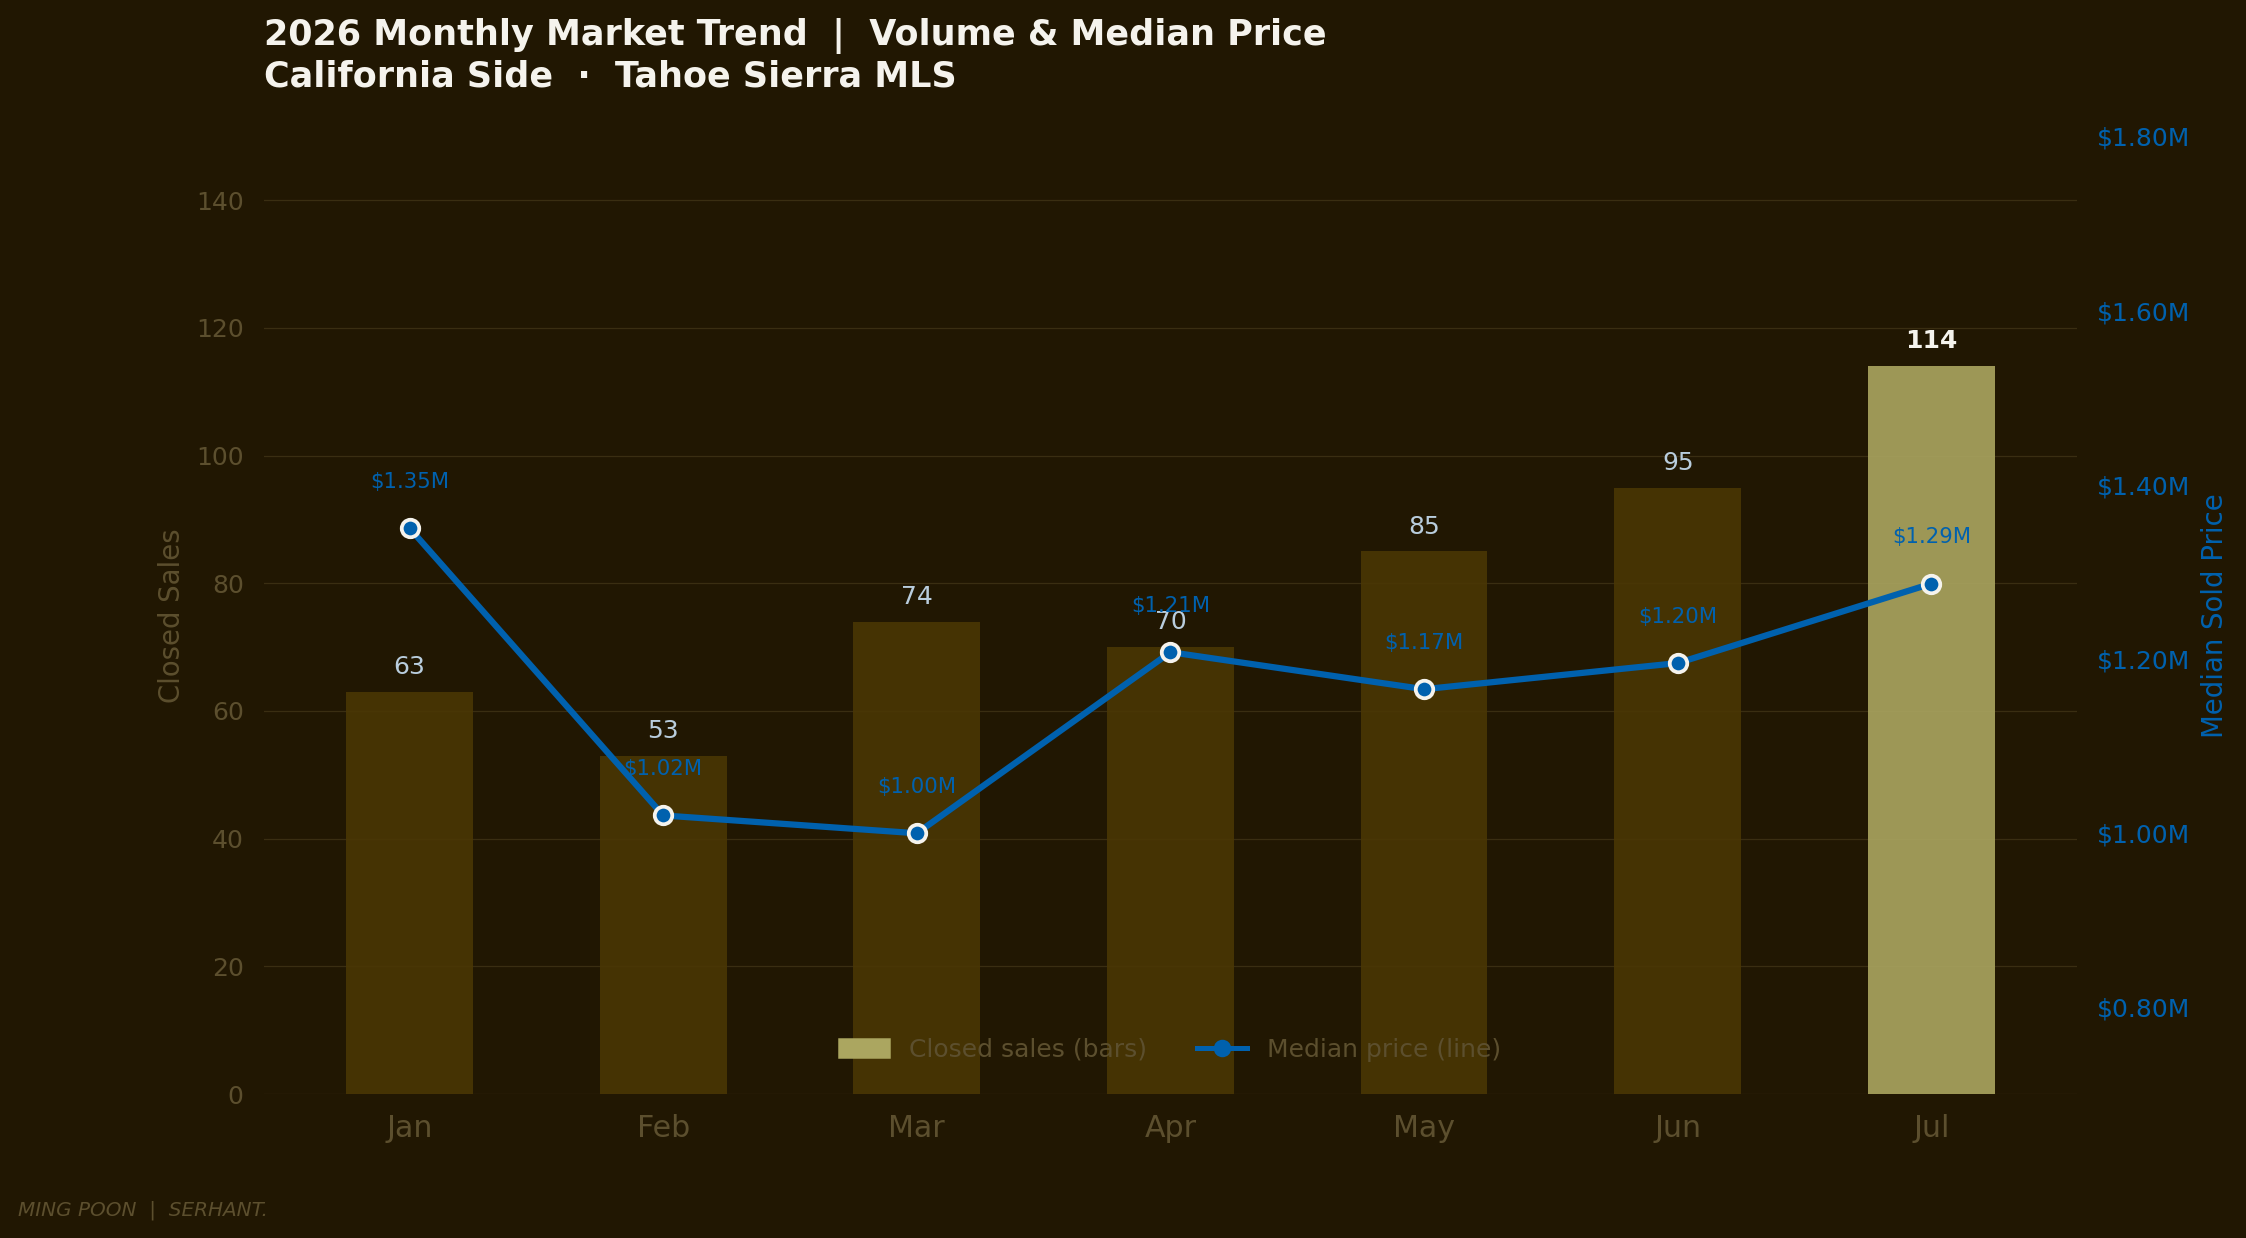
2026 Monthly Market Trend · Closed Sales & Median Price · Tahoe Sierra MLS, California Side
Year over year, the numbers are equally clear. July 2025 produced 97 closings at a $1,200,000 median. July 2026 produced 114 closings at $1,286,250. A 17.5% increase in volume and a 7.2% increase in median price — simultaneously. When both rise year over year in a normalized market, demand is real and durable.
THE BIFURCATION STORY IS CHANGING
For six months I have written about the two-market dynamic — sub-$2M as a seller's market, $2M+ as a buyer's market, the two-million-dollar line as the dividing geography of two entirely different conversations.
July started to resolve that picture.
The $2M+ segment averaged 84 days on market in Q1 of this year. In Q2, that dropped to 68 days. In July, it came in at 49. That is a 42% compression in average time to close over seven months, in a segment that was being written off in the spring as oversupplied and patient-optional. It was neither. It was a segment finding its price — and once it found it, buyers moved.
Twenty-nine properties closed above $2 million in July. Among the highest single-month totals for that segment in this dataset. The median closed price in the $2M+ range was $3,352,500. The average discount from original list was 2.6% — measurable, but meaningfully smaller than it was in January and February, when some of these properties were carrying 6–8% reductions from where they started. Sellers who held firm long enough found buyers. Sellers who repriced realistically found buyers faster.
The sub-$2M market continued doing what it has done all year: selling quickly and holding price. But within that range, something shifted in July that deserves its own attention.
The $1.5M–$2M tier produced 16 closings in July 2026. In July 2025, that same tier produced 6. A 167% year-over-year increase in a single price band. Buyers who were shopping at $1M–$1.5M twelve months ago are now closing at $1.5M–$2M. Whether that reflects being priced out of the lower band, an expansion of criteria, or simply an acceptance of where the market is — the result is the same. The upper end of the sub-$2M range is the most active it has been since the 2022 peak, and it is moving with conviction.
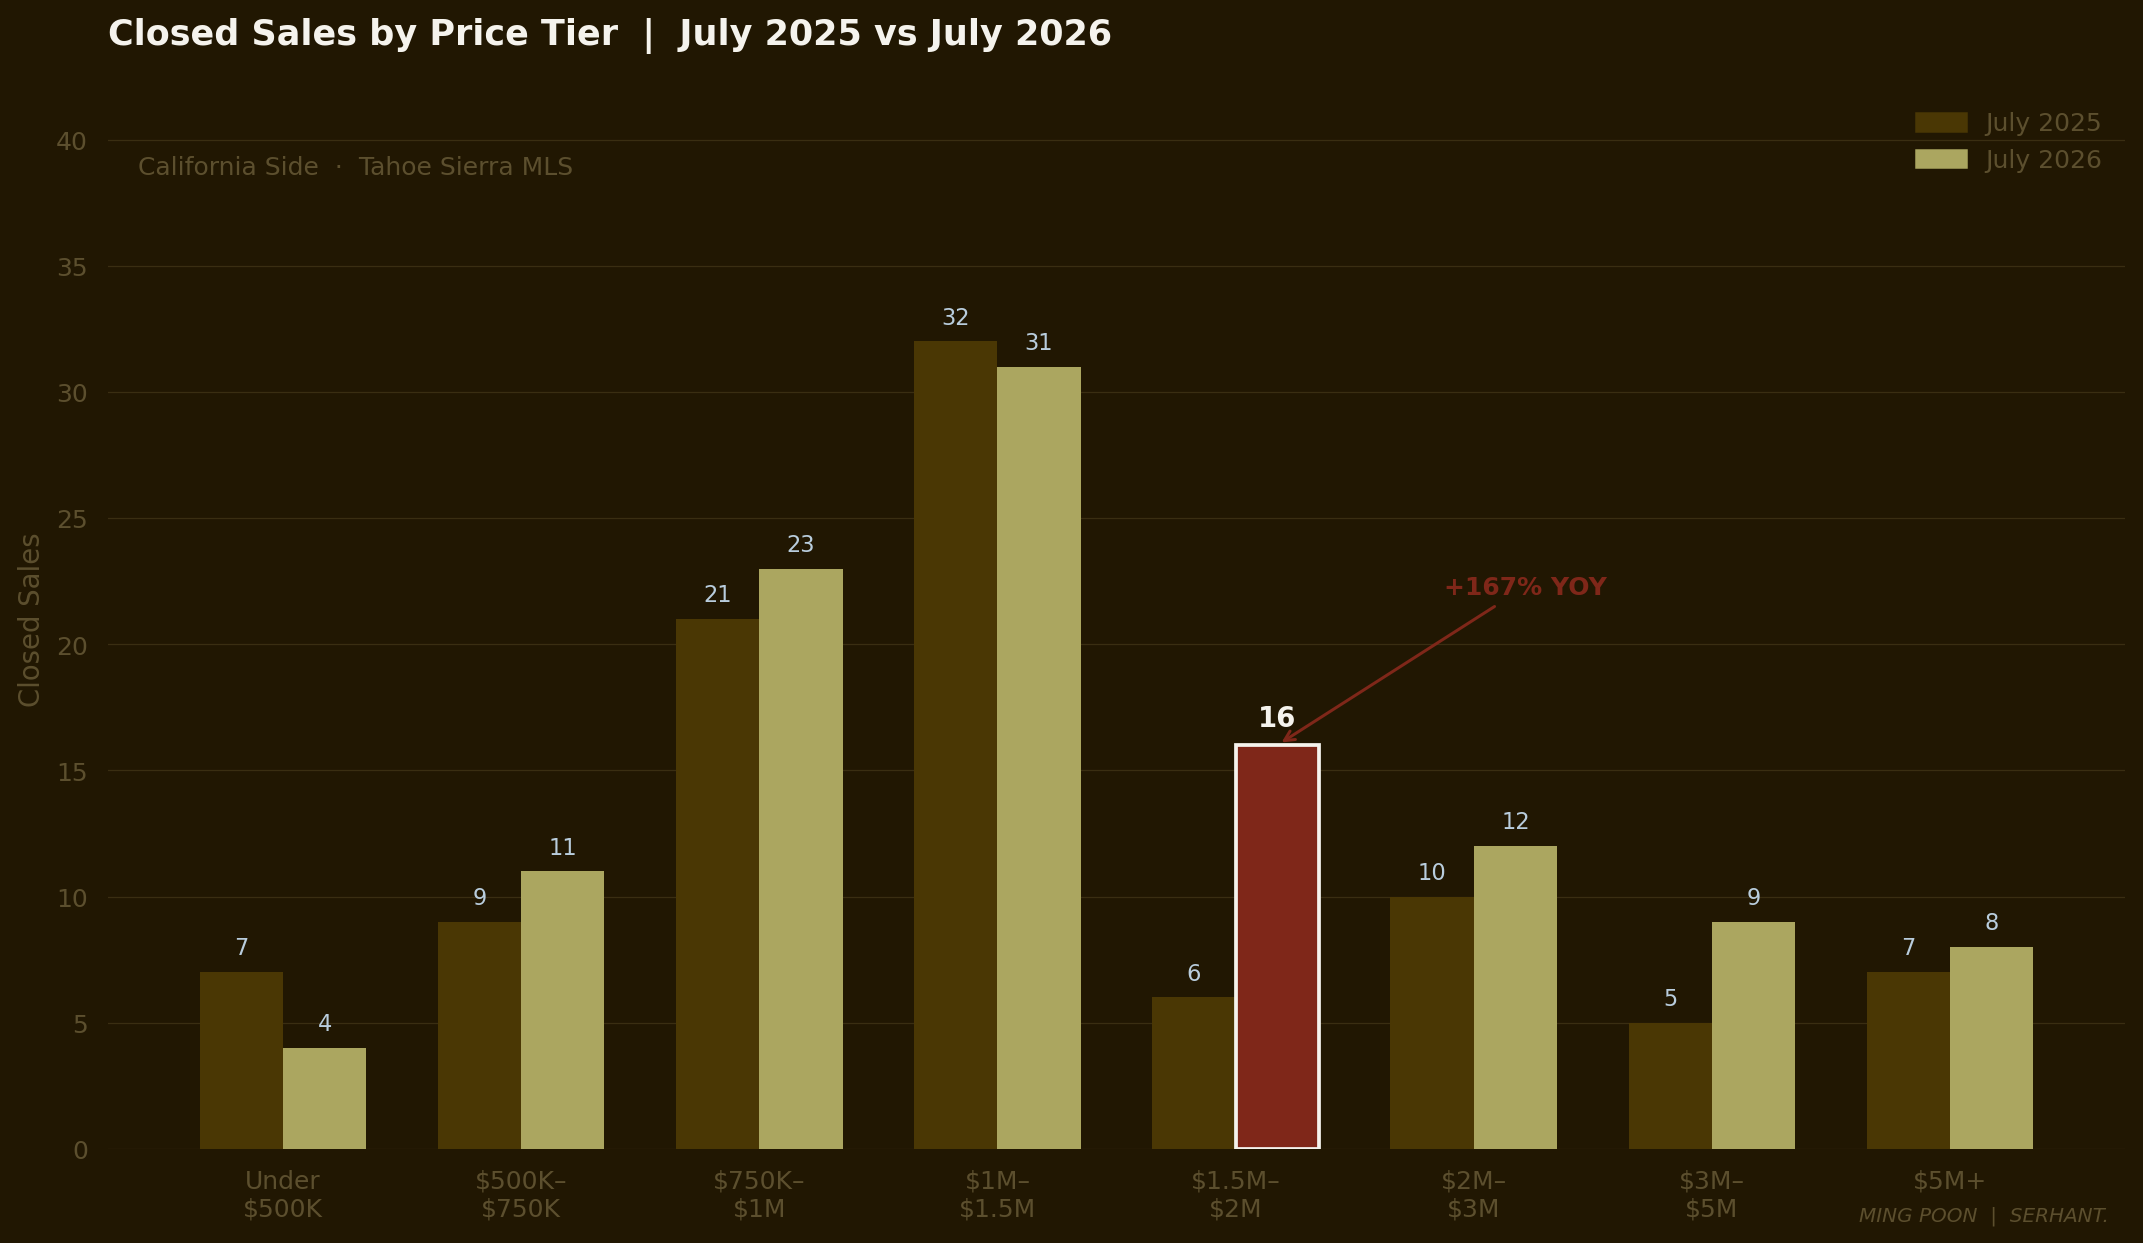
Closed Sales by Price Tier · July 2025 vs July 2026 · Tahoe Sierra MLS, California Side · $1.5M–$2M tier highlighted
The sub-$500K segment, meanwhile, produced just 4 closings in July. A year ago it was 7. The entry point of this market is rising and it is not coming back down. There is no inventory mechanism that produces more affordable Tahoe property. Land constraints, permitting timelines, and construction costs ensure that what gets built is expensive, and what gets sold at the lower end is what was already there — and there's less of it every year.
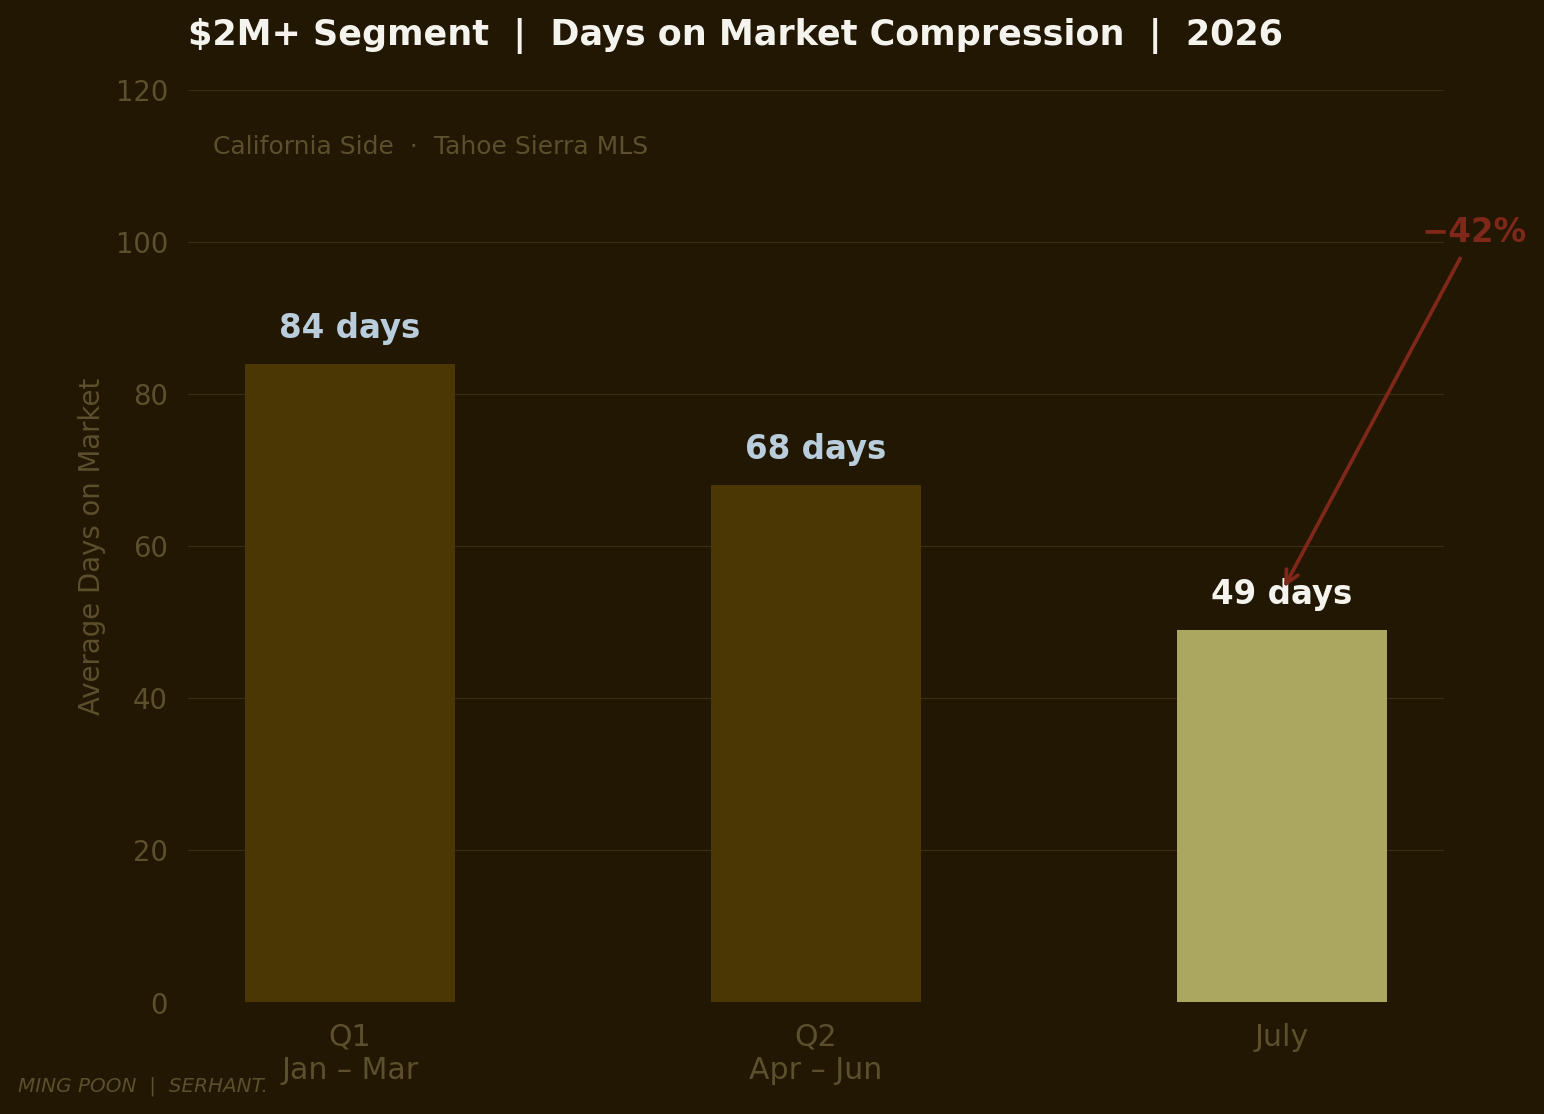
$2M+ Segment · Average Days on Market · Q1 through July 2026 · Tahoe Sierra MLS, California Side
THE LAKEFRONT LAYER
Address | City | Sold Price | DOM | vs. Ask |
|---|---|---|---|---|
3540 West Lake Blvd | Homewood | $10,500,000 | 6 | At ask |
13351 Donner Pass Road | Truckee | $7,400,000 | 7 | +$500K over |
14578 South Shore Drive | Truckee | $6,800,000 | 0 | At ask |
6400 West Lake Blvd | Tahoma | $3,800,000 | 151 | -9.4% |
8308 North Lake Blvd | Kings Beach | $2,415,000 | 11 | -3.4% |
9200 Brockway Springs Drive | Kings Beach | $975,000 | 8 | +0.6% over |
Six true Lake Tahoe lakefront closings in July on the California side. The range: $975,000 to $10,500,000.
That span is the whole story of the lakefront market compressed into a single month. At one end, a 798-square-foot Kings Beach property at $975,000 — the sub-$1M lakefront window that never stays open long — moving in 8 days at slightly above asking. At the other end, 3540 West Lake Boulevard in Homewood: 3,331 square feet on the West Shore, closed at $10,500,000, full ask, in 6 days.
Six days.
On a $10.5 million property. In what is supposedly a buyer's market for luxury. That transaction doesn't fit the narrative — which is exactly why it matters. When a generational West Shore property is brought to market priced with precision in peak summer, the buyer is there. They have been waiting. The property just has to deserve their attention.
13351 Donner Pass Road in Truckee closed at $7,400,000 — $500,000 over asking — in 7 days. Also lakefront, also South Shore, also not what spring's inventory data would have predicted. Evidence that the right property, priced right, in the right season, operates by different rules than the aggregate statistics.
And then there is 6400 West Lake Boulevard in Tahoma: 2,722 square feet, $3,800,000, 151 days on market before closing at a 9.4% discount from original ask. Same lakefront classification. Completely different trajectory. Condition, orientation, price point, and patience all shaped a different outcome. The lakefront market is not monolithic. Understanding what makes one property move in a week and another sit for five months is the work that actually matters on behalf of clients.
2026 YTD lakefront context: Twenty-three true Lake Tahoe closings on the California side through July 31. Total volume: $134.7 million. Median sold price: $3,550,000, compared to a full-year 2025 median of $3,011,500. Six closings above $10 million — a historically active pace for the trophy segment. The Kings Beach corridor along Brockway Springs Drive and the West Shore between Tahoe City and Homewood are generating the volume. The $19,650,000 close at 9820 Brockway Springs Drive in May and the $17,010,000 close at 1350 West Lake Boulevard in March anchor what has been a remarkable first seven months for the CA lakefront market.
TRUCKEE: THE MARKET WITHIN THE MARKET
Something worth naming directly: Truckee is no longer a supporting character in the Tahoe real estate story.
In July, four of the top ten closings by price were Truckee properties — none of them lakefront. Two were on Dunsmuir Way in Martis Camp. Two were golf-setting properties. Combined, over $26 million. The Valhalla Drive corridor in Martis Camp produced four of the top fifteen YTD sales across the entire dataset, ranging from $7.7M to $12.2M. A 4,136-square-foot street-setting home on Elsinore Court closed at $6,325,000. A 4,364-square-foot property on Dunsmuir Way closed at $7,872,000 in 20 days.
This is not a secondary market absorbing lakefront overflow. This is a distinct buyer making a distinct decision about a mountain community that offers something genuinely different: amenities that function year-round, a master-planned environment with controlled supply, and a buyer profile that skews toward full-time or primary relocation rather than second-home seasonality. When someone is making a life decision about where to base their family, Martis Camp has been the answer for a certain kind of buyer for a decade.
What's changed is the price level at which that decision now gets made. A $7.5M mountain property with no lake would have been an anomaly in 2016. In July 2026, it is a Tuesday.
WHERE THE MARKET HAS BEEN: THE FULL PICTURE
To understand where we are, you have to see the arc.
In July 2015, the median sold price was $547,000. Price per square foot was $315. The market was healthy, steady, and largely defined by Bay Area buyers mixing with locals in a traditional Tahoe summer cadence.
By July 2019 — the last clean pre-pandemic comparison year — the median had moved to $659,375 and price per square foot to $396. Measured appreciation, normal DOM around 18 days, a functioning market.
Then 2020 arrived. Two hundred and ninety-one July closings. The pandemic demand surge compressed DOM to 21 days even at that volume, pushed the median to $815,000, and began a price acceleration that would run through 2022.
July 2021: 192 closings, $1,070,391 median, 9-day DOM. The peak of the frenzy, though no one knew it at the time.
July 2022: 102 closings, $1,171,944 median, 12-day DOM. Volume dropped sharply as rates rose. Price held.
July 2023: 94 closings, $1,000,954 median. The only month in recent history where the July median dipped below $1 million. A brief exhale.
July 2024: 129 closings, $1,135,000 median. Volume recovery begins.
July 2025: 97 closings, $1,200,000 median. Volume dips but price climbs.
July 2026: 114 closings, $1,286,250 median. Volume recovery resumes. Price reaches an all-time high. Days on market compress to 13.5.
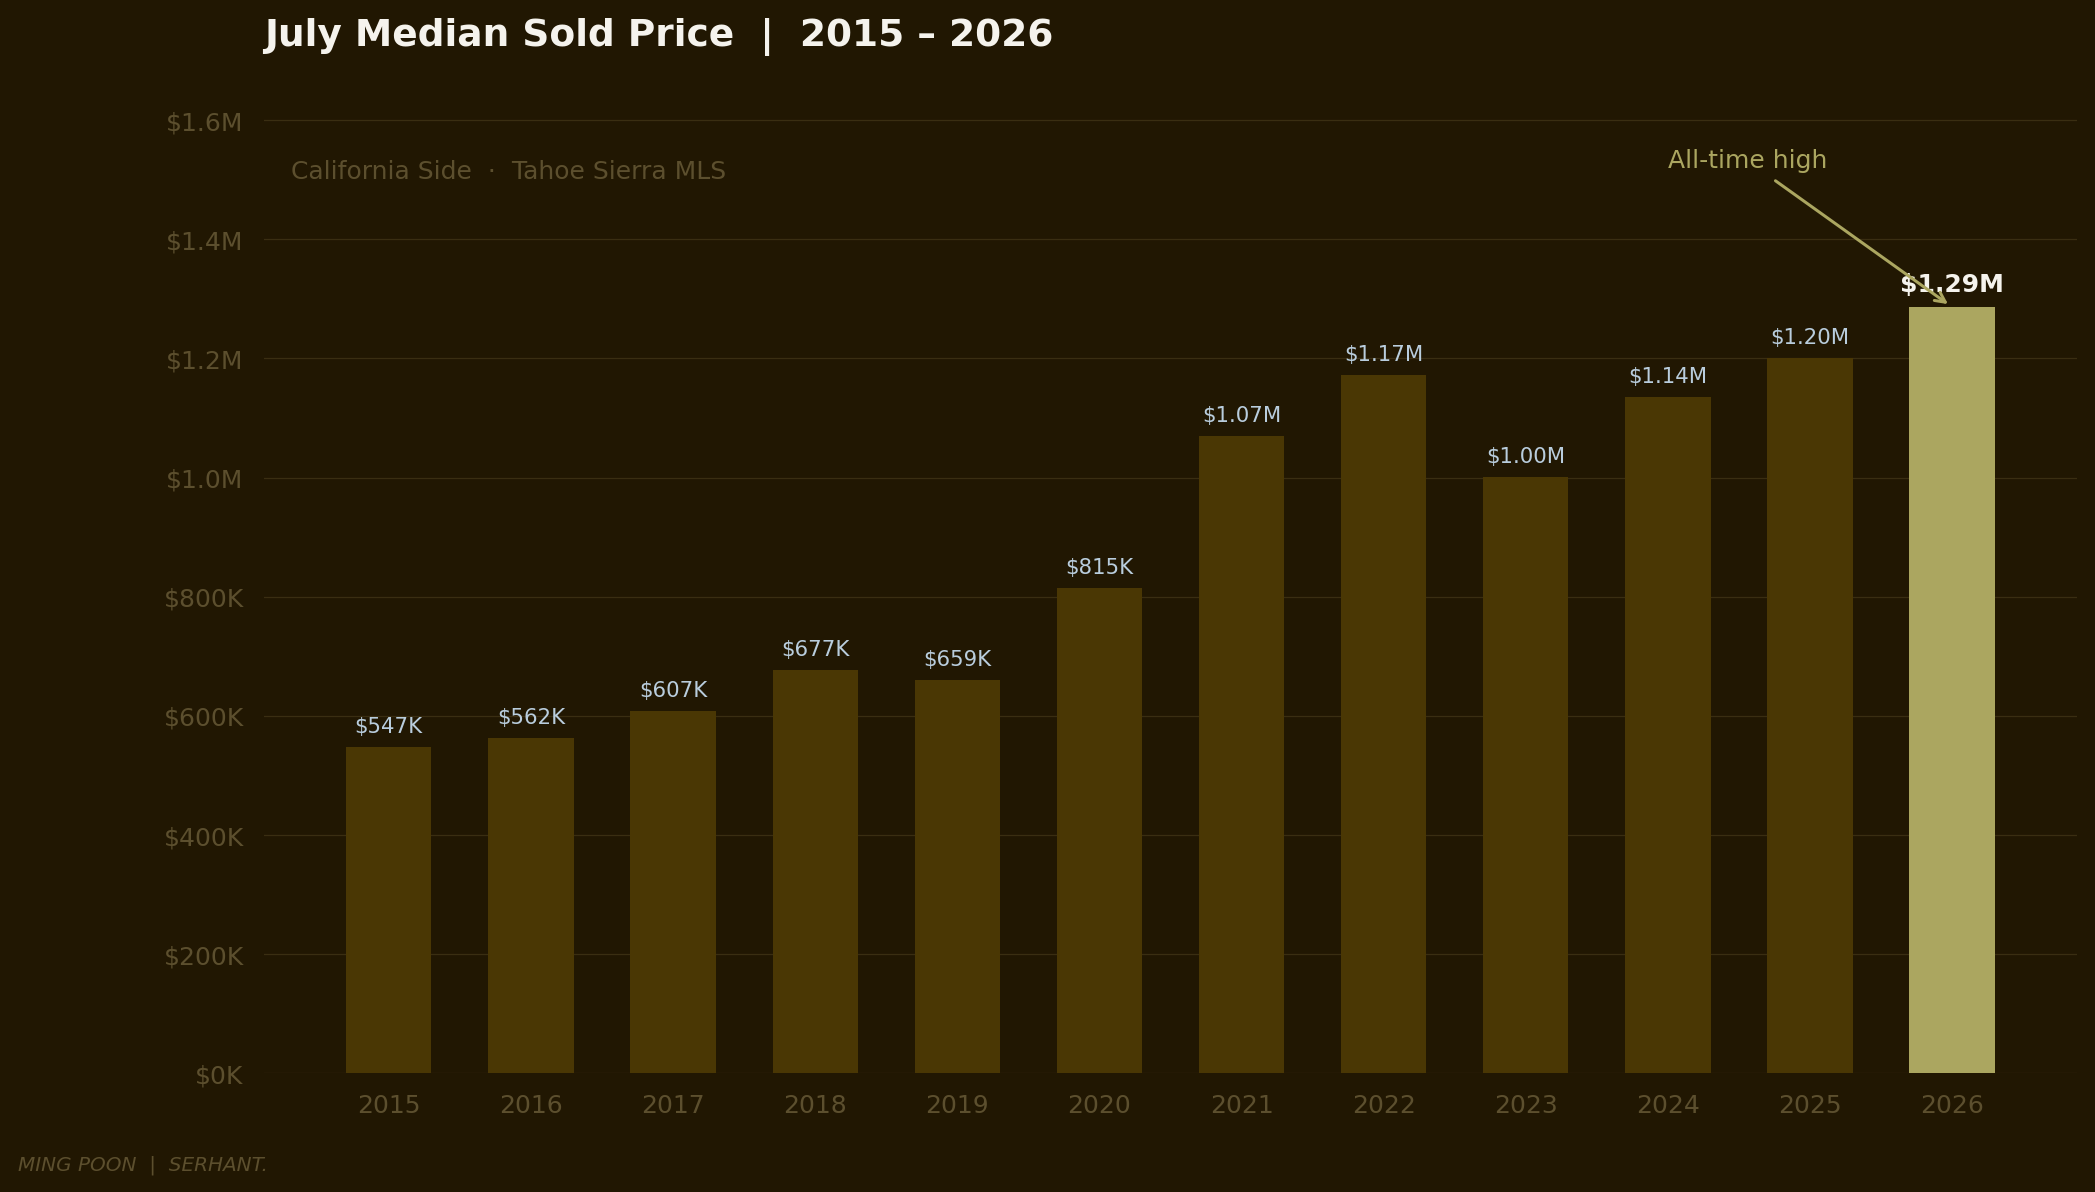
July Median Sold Price · 2015 – 2026 · Tahoe Sierra MLS, California Side
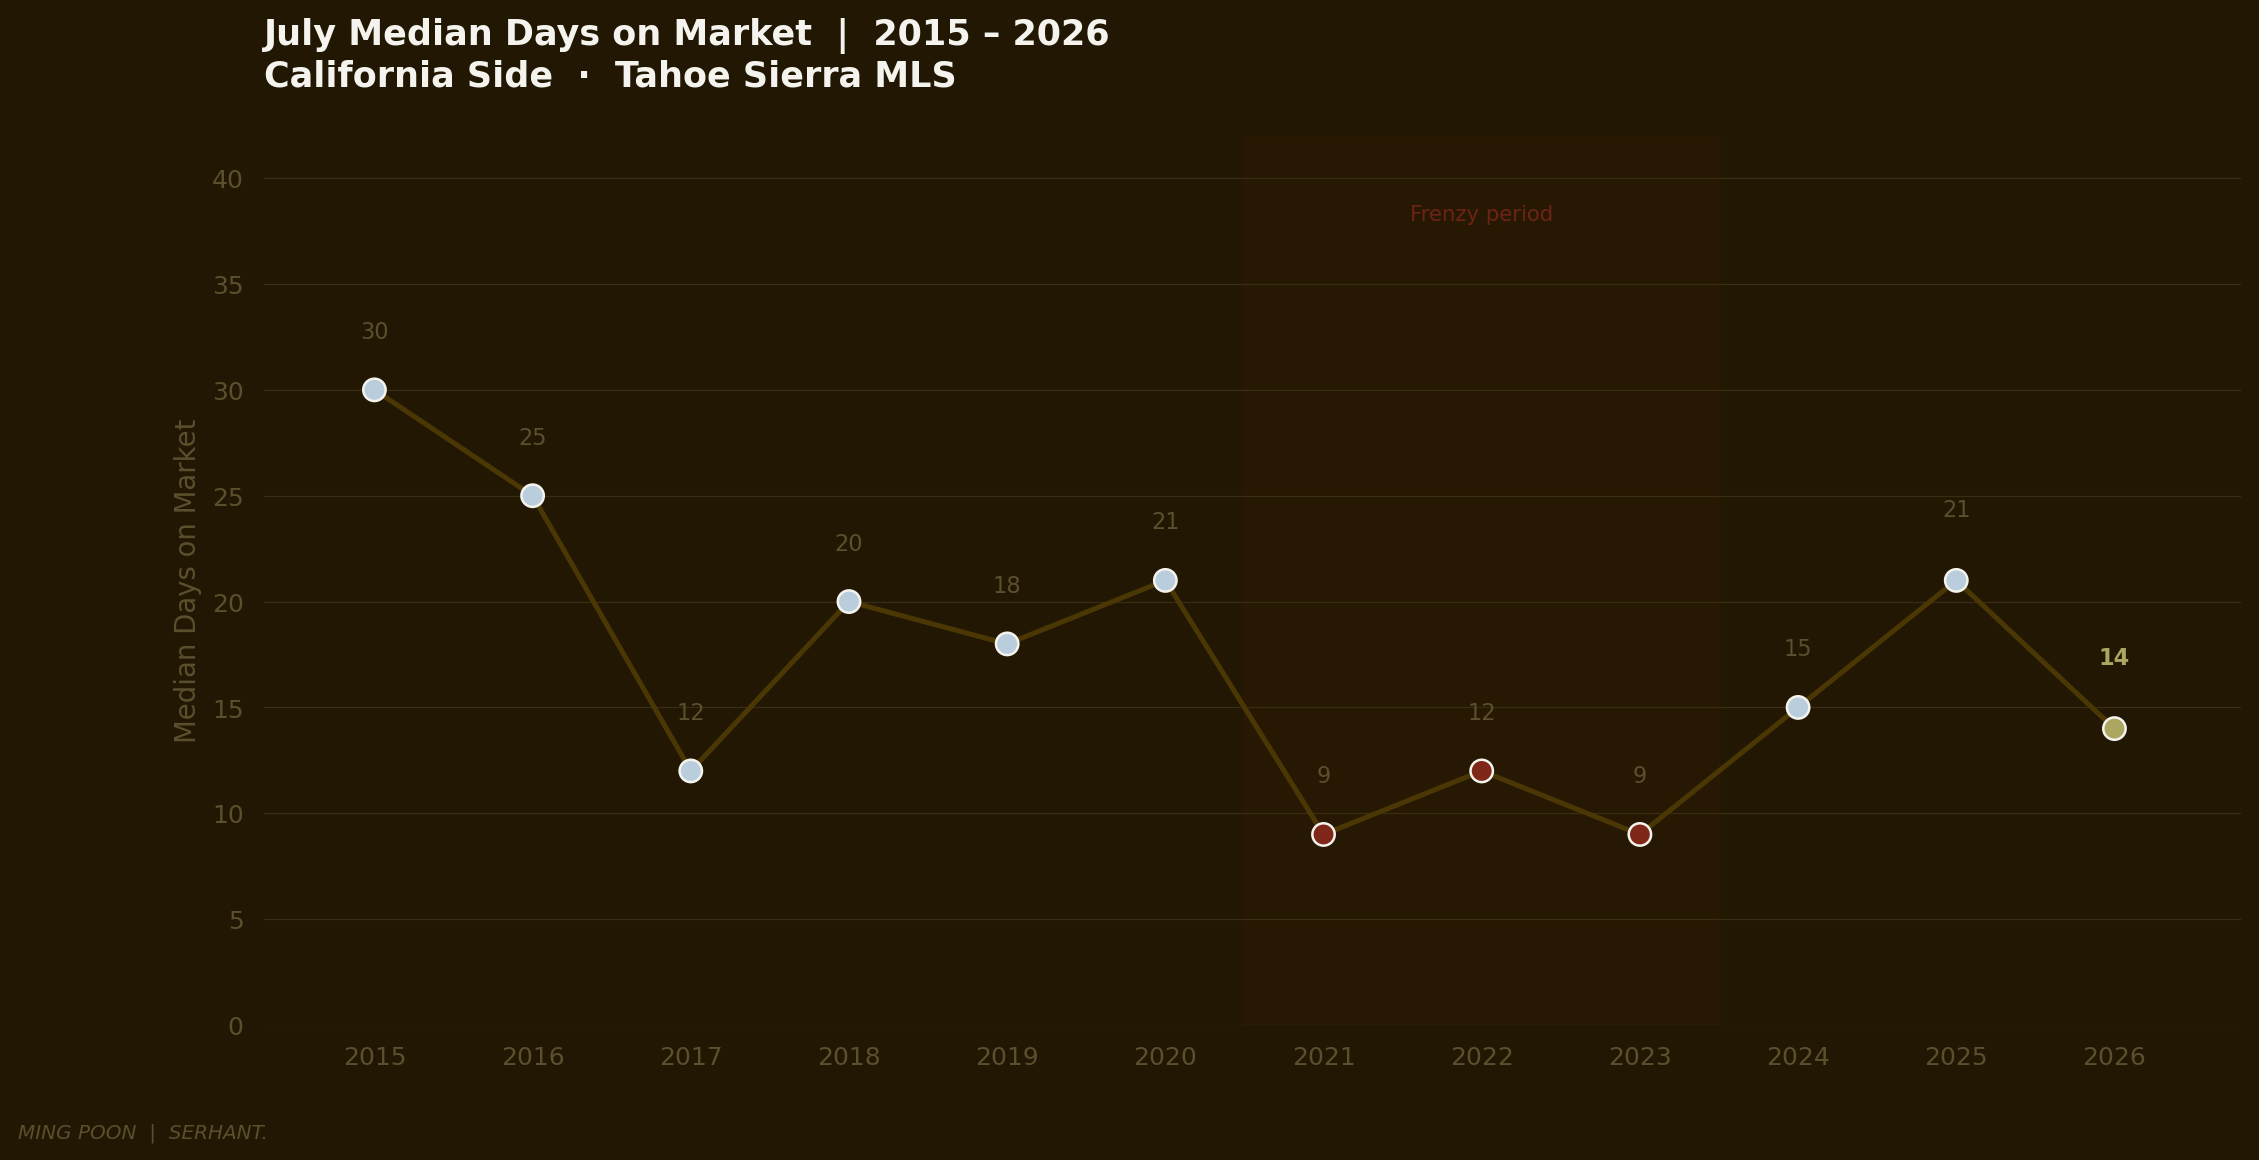
July Median Days on Market · 2015 – 2026 · Tahoe Sierra MLS, California Side · Frenzy period (2021–2023) shaded
The through-line: from July 2019 to July 2026, the median sold price has increased 95%. Price per square foot has moved from $396 to $653. In a market defined by constrained land supply, limited new construction, and a buyer pool that keeps expanding as remote work, wealth creation, and lifestyle prioritization reshape where people choose to live — this is not a surprise. It is a market doing exactly what supply-constrained resort markets do over time.
The 2024 dip is the detail that gets overlooked. Sixty-nine closings in June 2024 was the weakest June in the dataset. July 2024 at $1,135,000 was the low point of the post-pandemic price band. The 2026 recovery from that trough to all-time high medians — in volume and price simultaneously — is the story. Not a fluke of composition. Not a seasonal blip. A genuine return to strength.
THE YTD VIEW
Year-to-date through July, 2026 is the strongest volume year since 2022 at 554 closings.
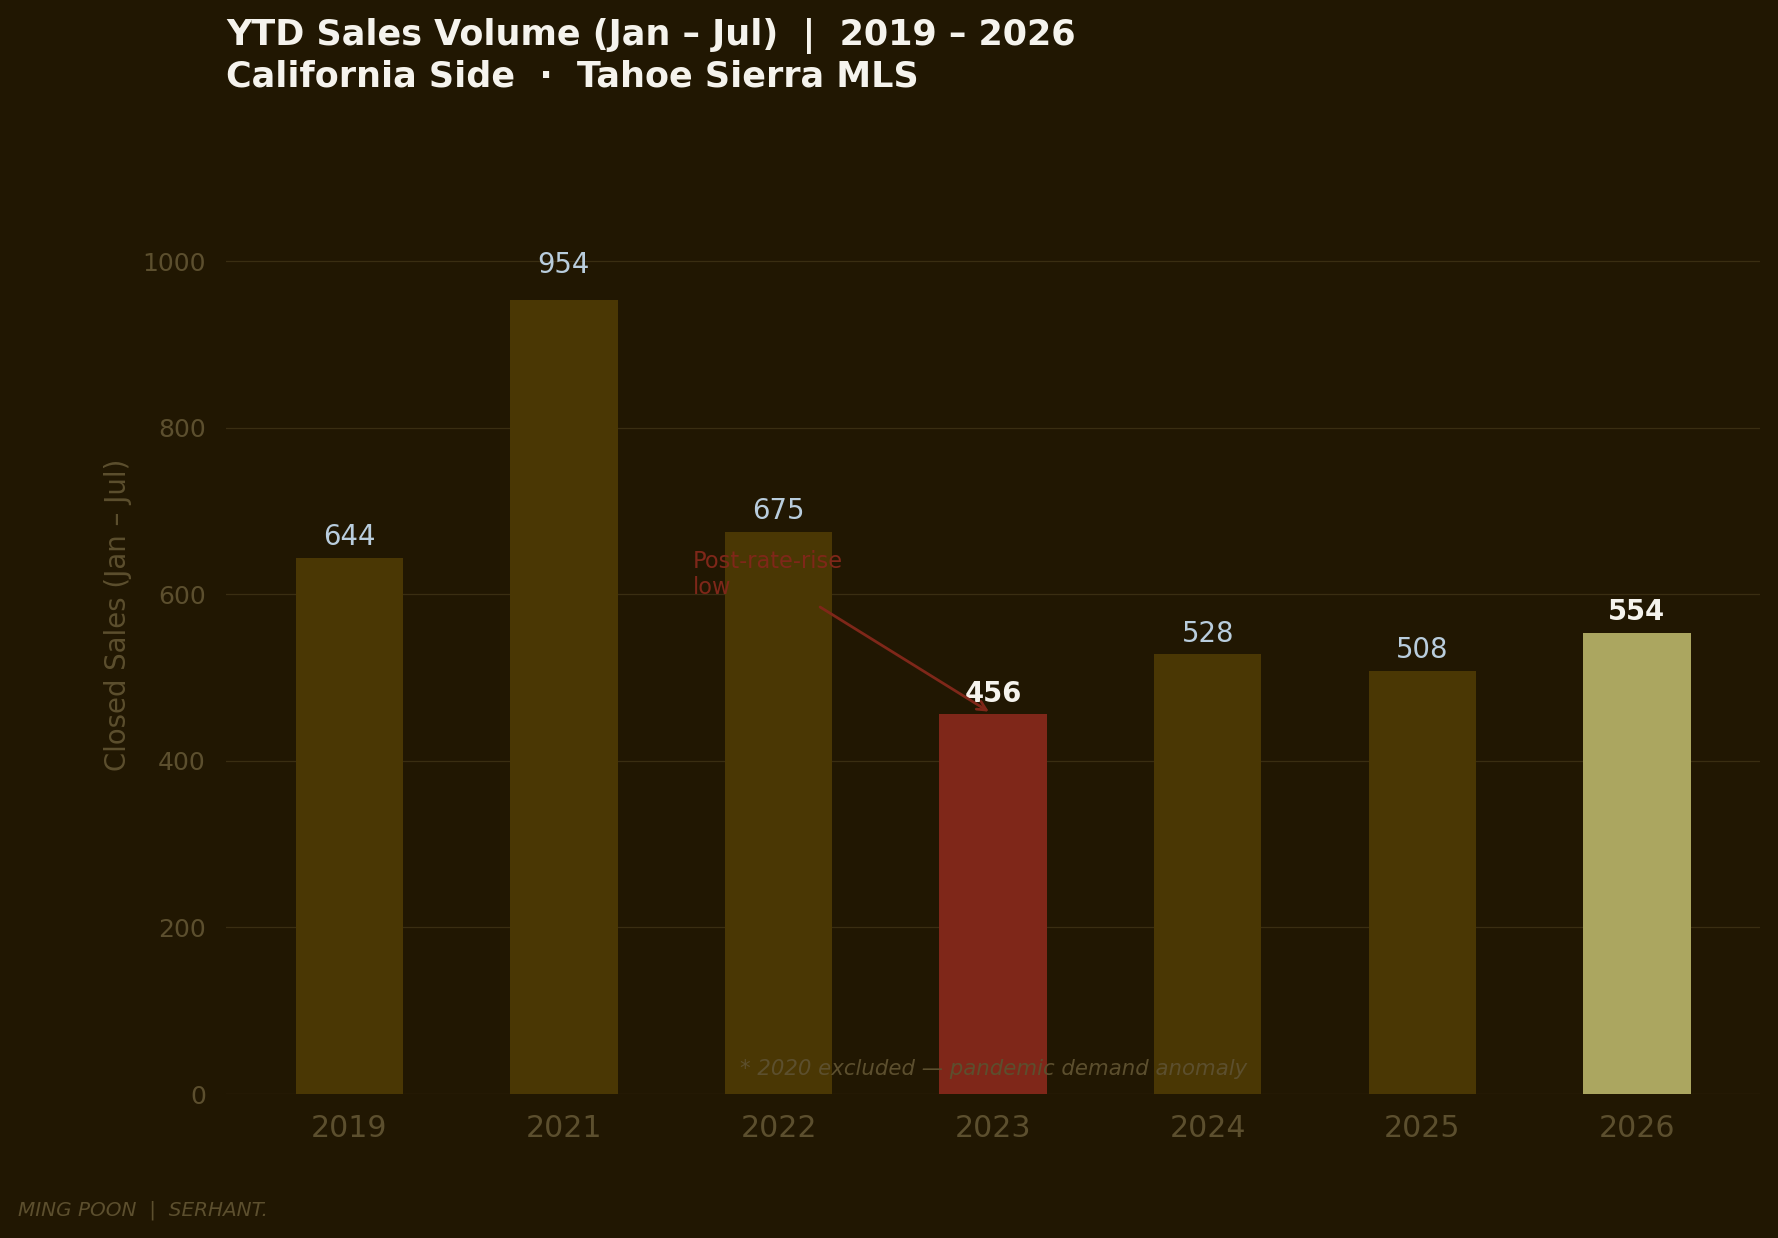
YTD Closed Sales (Jan – Jul) · 2019 – 2026 · Tahoe Sierra MLS, California Side · *2020 excluded — pandemic anomaly
The seven-month median of $1,197,500 is essentially flat year-over-year — the Q1 softness (slower DOM, lower medians through March) is still weighing on the cumulative figure even as July performed strongly. That softness is in the rearview mirror. The second half starts from a meaningfully stronger position than the first half.
$2M+ volume YTD stands at 130 closings, versus 123 in 2025 and 95 in 2024. If that pace holds through December, 2026 will be the most active $2M+ year since 2022. That is not a minor development. The luxury segment recovering in volume while also compressing DOM is the combination that changes the conversation with sellers who have been waiting.
WHERE IT'S GOING: PROFESSIONAL OPINION
The all-time high median in July is a signal, not a ceiling.
The buyers who are active right now are rate-resilient. A meaningful share of these transactions involve cash or significant equity positions from people who have made wealth and lifestyle decisions independently of mortgage rates. That buyer pool does not disappear when rates move fifty basis points. They recalibrate timing, not intent.
The $2M+ DOM compression — from 84 days in Q1 to 49 days in July — is the most important trend in this data that no one is talking about publicly. If that compression continues through August and September, the narrative about the luxury segment being stuck will be replaced by a narrative about it having found its footing. I think that is where we are heading. The sellers who repriced intelligently in Q2 are closing. The ones still holding at 2022 aspirational numbers will follow eventually, or they will wait another year.
The $1.5M–$2M band will be the most active tier in the second half of this year. The 167% YOY jump in July is not a one-month anomaly. It reflects a real upward shift in buyer capacity and expectation. If inventory in that range stays tight — which it will, because there is no production mechanism to create it — prices in that tier will continue to firm through the fall.
Fall will tell us something the summer cannot. September and October reveal the character of underlying demand. The buyers who only come to Tahoe in July are not the ones who build the fall market. Fall buyers are different — more deliberate, often with a longer horizon, frequently further along in their decision. If median DOM holds below 20 days into September, this is not just a summer story. It is a structural story.
If you are a buyer on the sideline waiting for a signal — this is it. The all-time high median in a market with 13.5-day DOM is not an invitation to wait for a dip. It is evidence that the dip may not come, at least not in the sub-$2M range where most buyers are looking. In the $2M+ range, you still have room. The DOM data says that room is closing month by month.
If you are an owner thinking about timing, the data answers the question more clearly than it has in two years. Peak pricing. Peak velocity. The luxury segment moving toward absorption even after a slow spring. There is no guaranteed better window ahead — there may be another one that looks similar, as there usually is in a market this durable, but timing that precisely is not a strategy. This window is open.
If you own lakefront property, six closings above $10 million on the CA side in seven months tells you the capital is here. The buyer who can pay what your property is worth is present in this market right now. The question is whether the property is ready to meet them.
There's a moment every summer on the lake — usually late afternoon, after the motorboats have cleared out and before the wind dies completely — where the water goes glassy and the light goes long and everything gets very still. It happens fast. It doesn't last long. If you're paying attention, you see it.
The July data says the window is open. The question — the only one that actually matters — is what it means for the life you're building around this place.
That's the conversation I'm here to have.
— Ming
All data sourced from the Tahoe Sierra MLS, California side. Nevada-side communities excluded. Lakefront classification uses the MLS Setting field; Split Lakefront properties and non-Lake Tahoe communities (Soda Springs, Donner Lake fractionals) excluded per standing methodology. Data covers closed sales through July 31, 2026. Historical data spans 2013–2026. Figures subject to revision as late-reported sales are recorded.
Ming Poon | SERHANT. | [email protected]
Disclaimer: The Tahoe Truckee Brief is prepared by Ming Poon for informational and editorial purposes only. Market statistics are derived from Tahoe Sierra MLS data and are deemed reliable but not guaranteed. Data may change as listings are updated, corrected, or reported after publication.
Unless otherwise noted, this report focuses on residential real estate activity within the Tahoe Sierra MLS and excludes Incline Village, Crystal Bay, South Lake Tahoe, and other markets outside the stated Tahoe-Truckee reporting area. Lakefront references are limited to Lake Tahoe and Donner Lake lakefront sales, including applicable lakefront condo/PUD and split-lakefront properties, and exclude Serene Lakes, Soda Springs, and other non-Tahoe/Donner lakefront properties.
This report is not intended as legal, tax, financial, investment, or appraisal advice. Real estate decisions should be based on the specific property, current market conditions, professional guidance, and the reader’s individual objectives. Buyers and sellers should independently verify all information before making decisions.